
Goldman Puts Almonty At “Center” Of Western Tungsten Race
Three weeks after Jefferies chemicals and materials analyst Laurence Alexander initiated coverage of Almonty Industries with a “Buy” rating and a 12-month price target of $26.25, framing it as a play on the “Western Tungsten Re-Shoring Trade,” Goldman Sachs launched coverage early Thursday, describing the miner as “at the center of the Western tungsten investment narrative.”
Goldman metals and steel analyst Nick Cash notes that Chinese policy restrictions have fueled supply concerns and an eightfold increase in tungsten prices since the start of 2025:
ALM sits at the center of the Western tungsten investment narrative as policy actions taken by China have resulted in global supply concerns, causing the price of tungsten to increase 8x since the beginning of 2025.
ALM owns one of the most important tungsten development asset outside China, the Sangdong mine in South Korea
However, we believe the stock is increasingly reflecting a continuation of today’s exceptional tungsten market as well as an aggressive production profile for Sangdong.
Almonty’s Sangdong mine in South Korea is key to conflict-free tungsten supply for the West as Beijing has ramped up restrictions that collide with the upcU.S.ing US rearmament cycle.
He cautioned that his estimates diverge from Wall Street consensus in two areas:
- We expect tungsten prices to normalize as new mine supply, recycling and refining capacity respond to current economics and
- We expect Sangdong’s ramp to progress more gradually than market expectations. While we remain constructive on the strategic value of ALM’s asset base, we believe current valuation already discounts much of that upside potential.
Almonty has moved to expand conflict-free tungsten supplies through a multiyear, take-or-pay offtake agreement with Sandvik Group subsidiary, centered on recovering tungsten from existing tailings at its Los Santos mine in Spain. The miner has also established a strategic partnership with Rwanda’s government, while South Korea approved the miner earlier this week to supply Western markets.
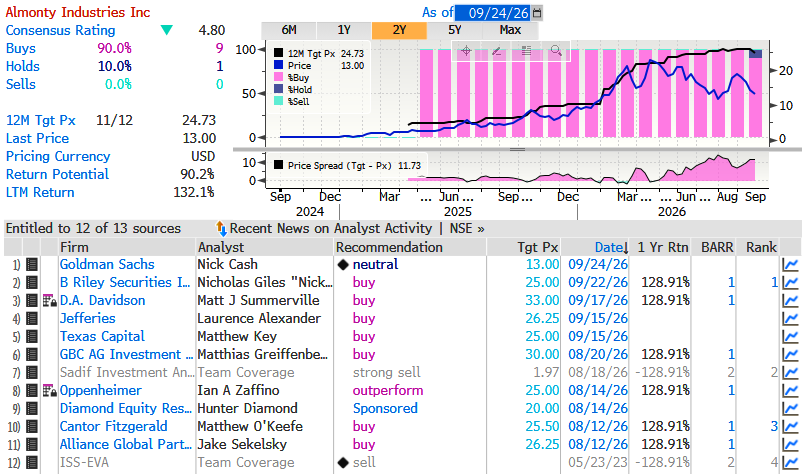
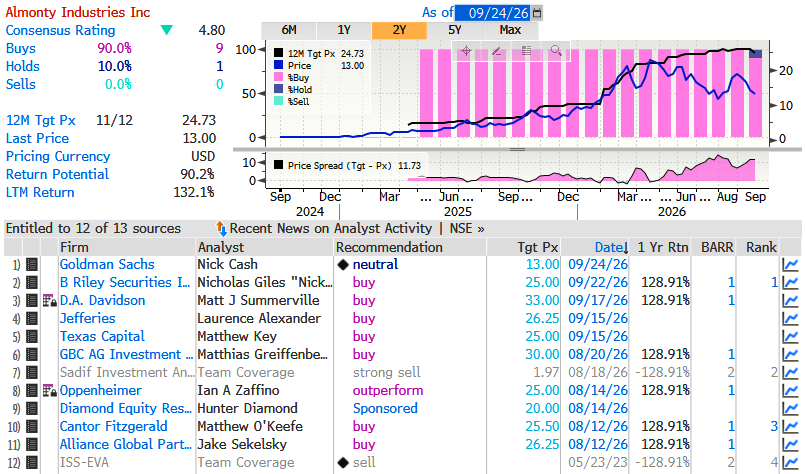
Goldman’s valuation stands well below the broader Street consensus. Bloomberg data show a consensus 12-month price target of $24.73, compared with Nick Cash’s $13 target. Almonty’s analyst coverage now comprises 9 “Buy” ratings and one “Hold” rating following Goldman.
Jefferies’ Alexander noted earlier this month, “Almonty offers long-dated leverage to Western tungsten supply-chain re-shoring through Sangdong, Panasqueira, Browns Lake, and planned downstream oxide capacity. China controls ~80% of supply, while defense procurement restrictions begin in 2027.”
Almonty shares fell 6.5% to around $12.74 on Thursday morning, slightly below Goldman’s 12-month price target. The broader space, viewed through the lens of the VanEck Rare Earth and Strategic Metals ETF (REMX), has also declined in the back half of summer.
Tyler Durden
Thu, 09/24/2026 – 11:25

