
CoreWeave Founders Cashed Out $3.3 Billion Before The Meltdown
Before CoreWeave imploded, its three co-founders had been busy dumping stock, a lot of it, totaling $3.3 billion since the company’s March 2025 IPO. The AI cloud provider rents access to Nvidia-powered data centers that fuel the AI circular financing scheme. Its unsecured bonds due in 2032 have crossed into distressed territory, and its five-year CDS spreads have blown out as debt levels at hyperscalers and neocloud providers come into question.
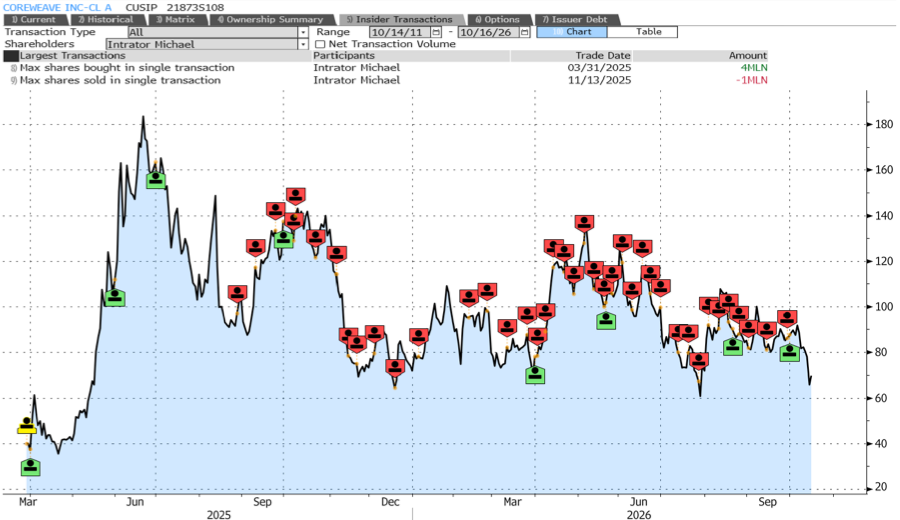
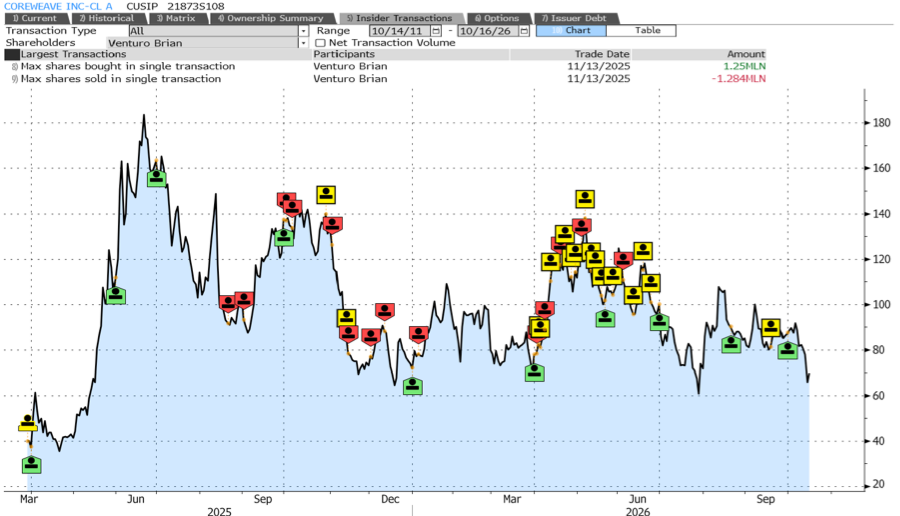
Michael Intrator, Brian Venturo and Brannin McBee sold $2.4 billion this year alone, according to Bloomberg’s new report on corporate filings.
Intrator has sold more than $907 million in shares this year. McBee’s sales since the IPO total $1.06 billion, equivalent to 40.4% of his undiluted stake at the listing. Venturo has sold more than $1.2 billion, representing over 35% of his original holding.
As musician Kenny Rogers once sang, “You got to know when to hold ’em, know when to fold ’em, know when to walk away, and know when to run…”
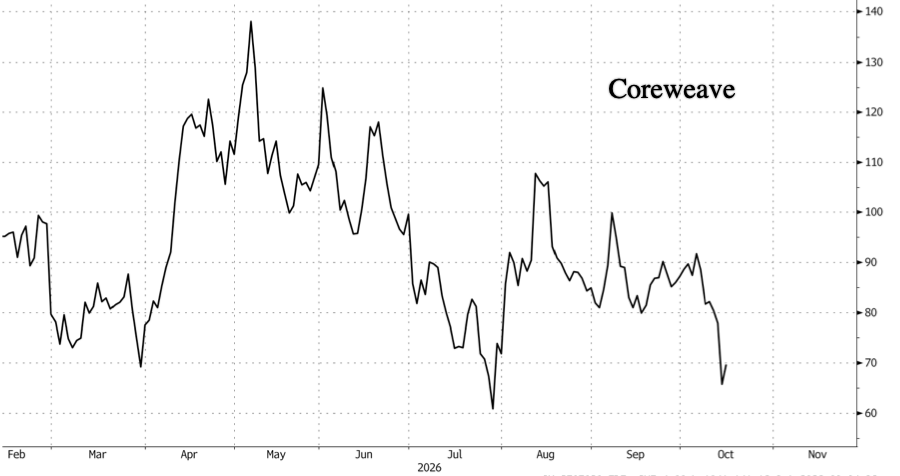
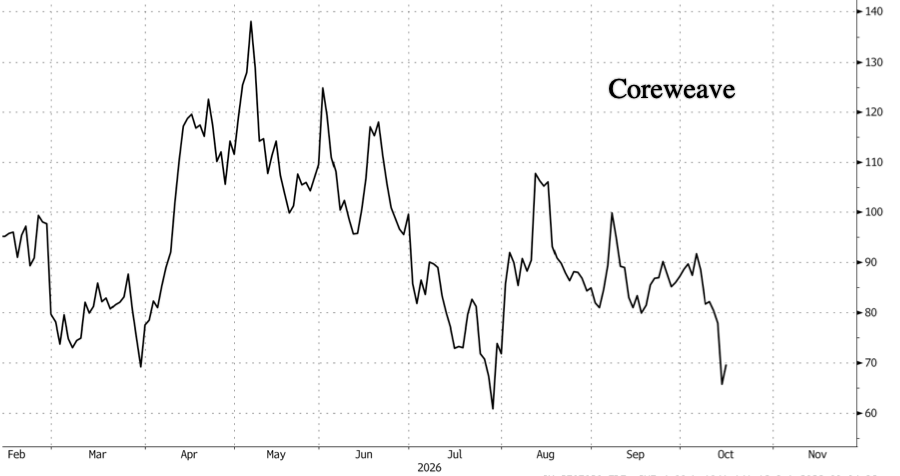
CoreWeave shares have plunged more than 50% from their May peak, erasing $15 billion of the founders’ paper wealth.
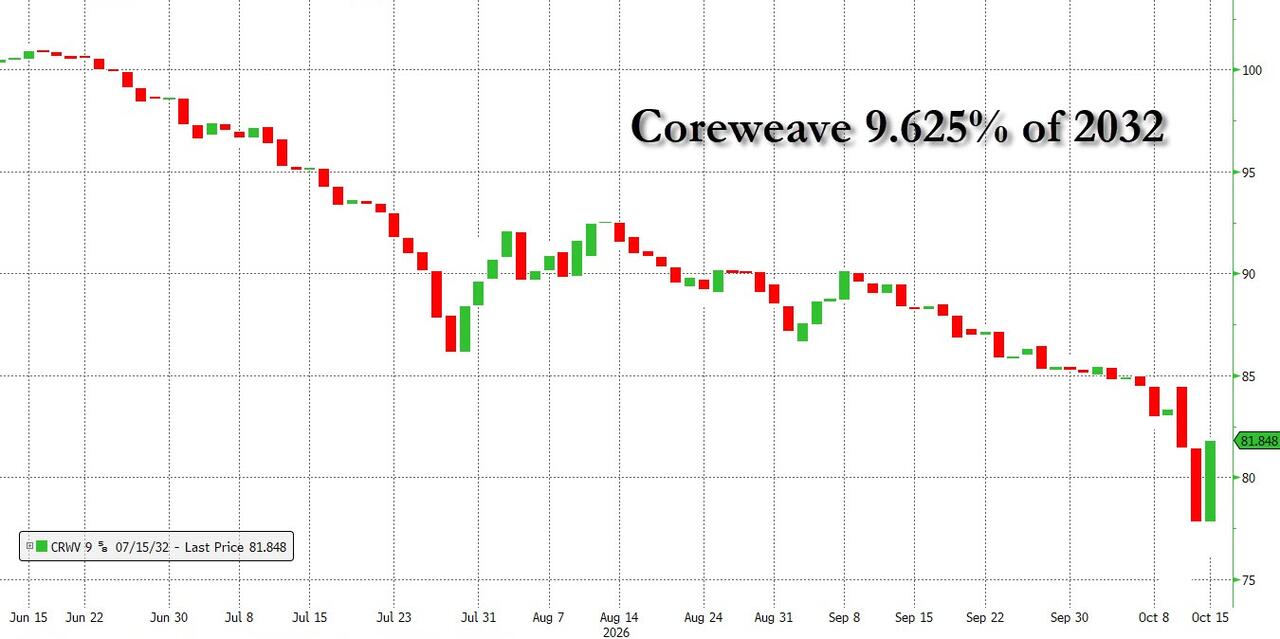
By late in the week, CoreWeave’s 2032 bonds traded at deeply distressed levels. The 9.625% notes due in 2032 tumbled to nearly 76 cents on the dollar, a level that typically signals distress.
CoreWeave’s CDS spread had also reached a record of 1,117 bps by the end of the week, implying 63% odds of a default within five years.
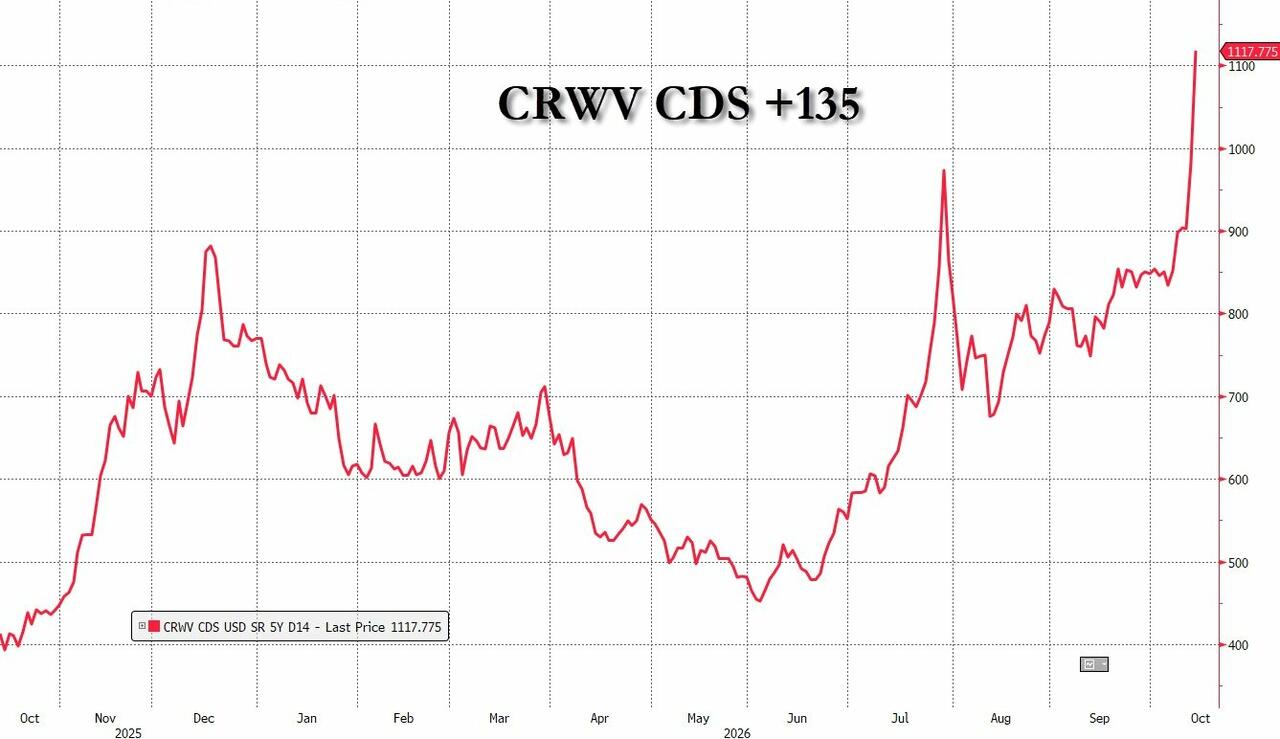
On Thursday, we laid out why Gartner expects over 80% of neoclouds to fold, and we hinted at the big problem: CoreWeave is the borrower on its own unsecured bonds, and it is also the tenant that is supposed to pay the rent on a big chunk of the junk-rated data center bonds issued by other companies. If CoreWeave’s cost of capital is “decreasing” at 16%, what does that make the cost of capital for the companies whose bonds are backed by CoreWeave’s lease payments?
Related:
Deutsche Bank chimed in:
Deutsche Bank: “CoreWeave no doubt will need additional capital to fund existing backlog over the next 12-18 months,” with NTM operating cash flow of ~$10 billion against required capex of $45 billion. That is a $35 billion funding gap: if even half of it had to be raised at the ~15% where CoreWeave’s unsecured bonds now trade, the extra interest bill would be roughly $2.6 billion a year, more than the entire $2.1 billion loss analysts expect CoreWeave to post this year. Or it could just sell more stock
— zerohedge (@zerohedge) October 16, 2026
Charting CoreWeave’s top executives dumping stock:
Michael Intrator
Brian Venturo
Brannin McBee
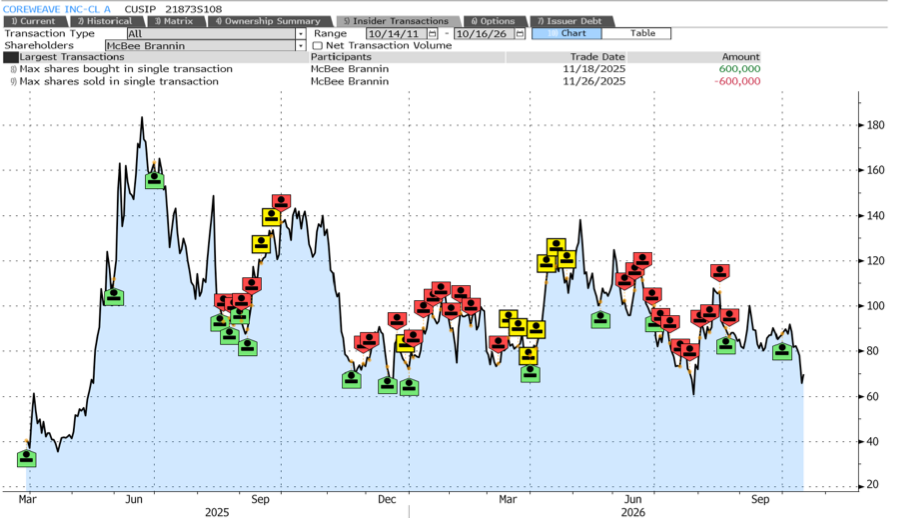
Kenny Rogers said it best: “You got to know when to hold ’em, know when to fold ’em, know when to walk away, and know when to run…”
Tyler Durden
Fri, 10/16/2026 – 08:20

