
SpaceX Jumps On Blowout Quarter As AI Sends Revenue, EBITDA Soaring
As we wrote in our preview, hopes are high for what SpaceX will report today. The company is expected to report solid revenue growth, however more than offset by far more solid capex growth which will result in SpaceX burning almost a quarter trillion over the next 3 years as it builds out its data center capacity. Notably, SpaceX could post its first quarterly profit today – though this is only its second earnings report as a public company. Wall Street expects earnings of 15 cents a share, or about $1.9 billion in net income, compared with a $541 million loss last quarter.
Besides the top and FCF lines, Deutsche’s list of “other areas of focus” is a good checklist of what else to look for:
- AI: neocloud pricing and new contracts, the Cursor contribution, Grok Bot adoption, and the data center capex outlook (read: any hint that 2027 capex starts with a “2”).
- Launch: timing of the next few launches after Flight 14; Flight 15 looks set for mid-/late November, though DB doesn’t expect a second-stage catch.
- Connectivity: after the $8 billion Grain spectrum deal, “additional color on management’s next move(s) in the US (build vs. buy),” which is something the wireless carriers will be listening to closely.
Additionally, investors are seeking additional hints about a potential Tesla and SpaceX merger. Today’s earnings are happening just a few days after Tesla unveiled its new Roadster, which incorporated SpaceX gas thrusters that allowed the vehicle to hover and do barrel rolls in the air. Following the event, a bunch of Tesla and SpaceX executives and employees started following each other on X, according to an account that monitors tech executives. DB said that the timing as “mainly a function of valuation differentials and politics (may want to avoid a potential Democrat-led administration taking over post Trump).”
Elon Musk has talked a lot about the “convergence” of his businesses over the last year. Meanwhile SpaceX and Tesla are already collaborating on one of Musk’s most ambitious projects: the Terafab, which aims to mass produce semiconductor chips in the US to be used in his companies’ various products.
Don’t expect to see much, if any profit: Starlink satellite-internet service is SpaceX’s only profitable business. The militarized version of Starlink, called Starshield, came under increased scrutiny last week after Ukrainian President Volodymyr Zelenskyy accused the White House and Musk of placing restrictions on the technology in Ukraine, disrupting military operations. Both Musk and Trump have denied involvement, igniting a firestorm over who controls the technology that has become indispensable to Ukraine’s war against Russia.
As for the market’s reaction, recall that SPCX shares slumped 14% the day after its first earnings release in August, in part over fears that insiders would sell shares after the earliest of many lockup expirations. Those fears were quickly calmed when the shares rebounded, but the setup heading into this quarter’s results is similar to last time. On Wednesday, an additional 1.3 billion shares, representing 28% of those subject to the 180-day lock-up period, will become available to trade.
So with all that in mind, here is what SpaceX just reported for Q3, its second quarter as a public company. For the most part a solid beat across the board, blowing past Wall Street expectations, and posting its first quarterly profit, $4.4 billion, or 35 cents a share, more than double estimates, while spending a massive $20 billion on capex
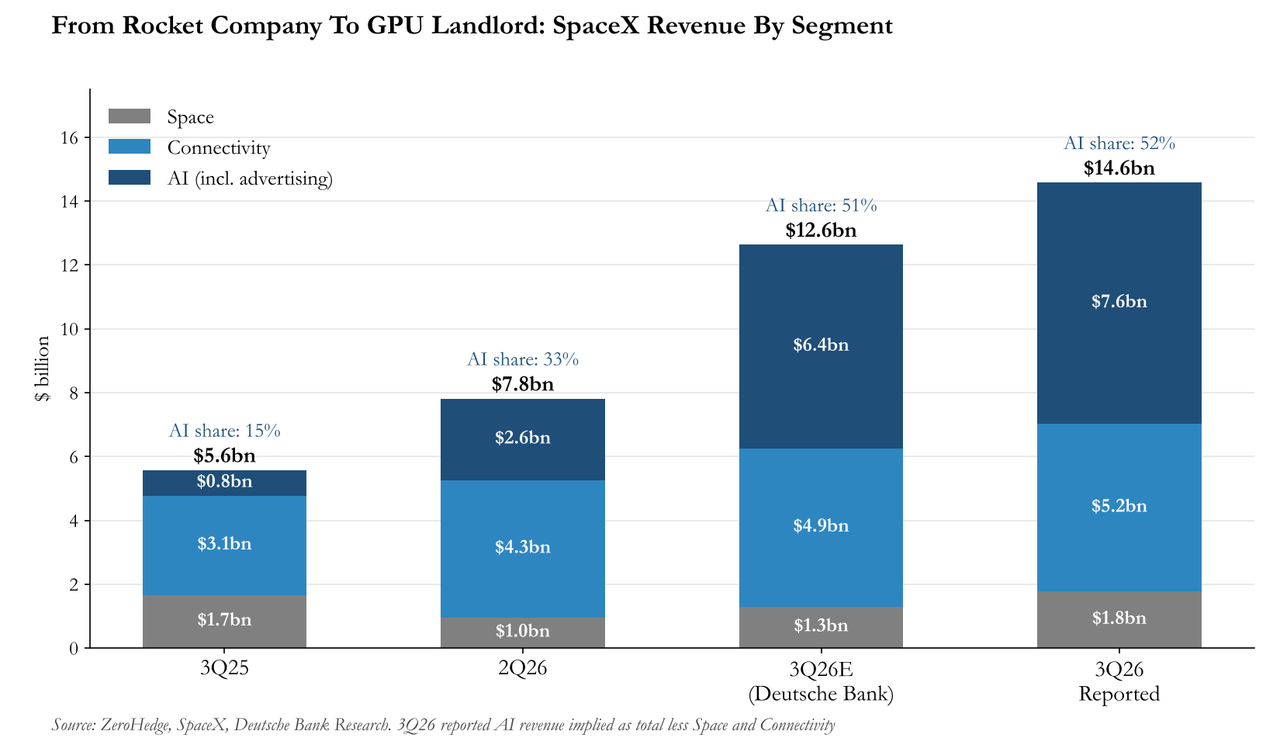
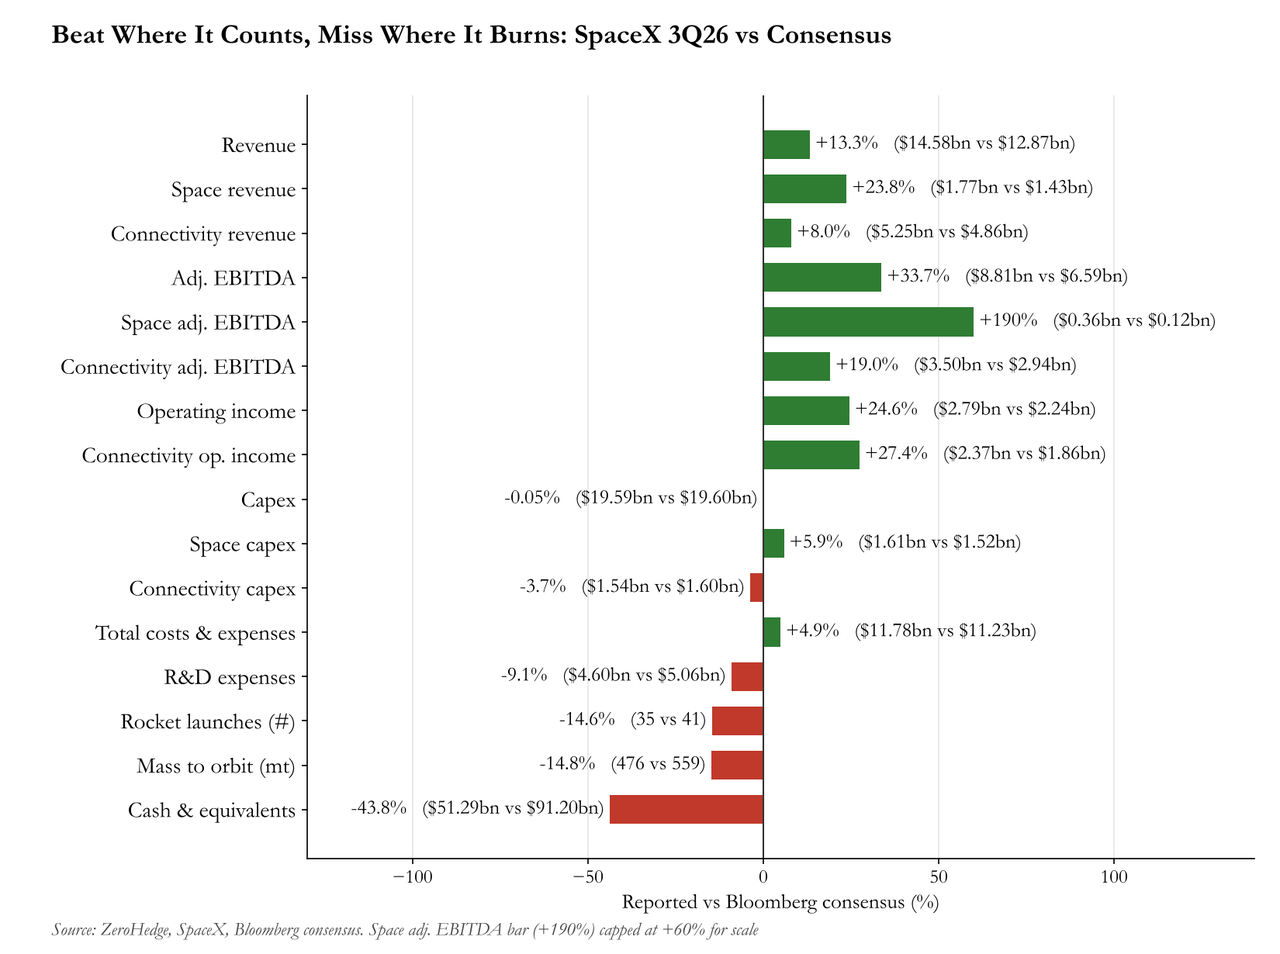
- Revenue $14.58 billion, beating estimates of $12.87 billion
- Space revenue $1.77 billion, beating estimates of $1.43 billion
- Connectivity revenue $5.25 billion, beating estimates of $4.86 billion
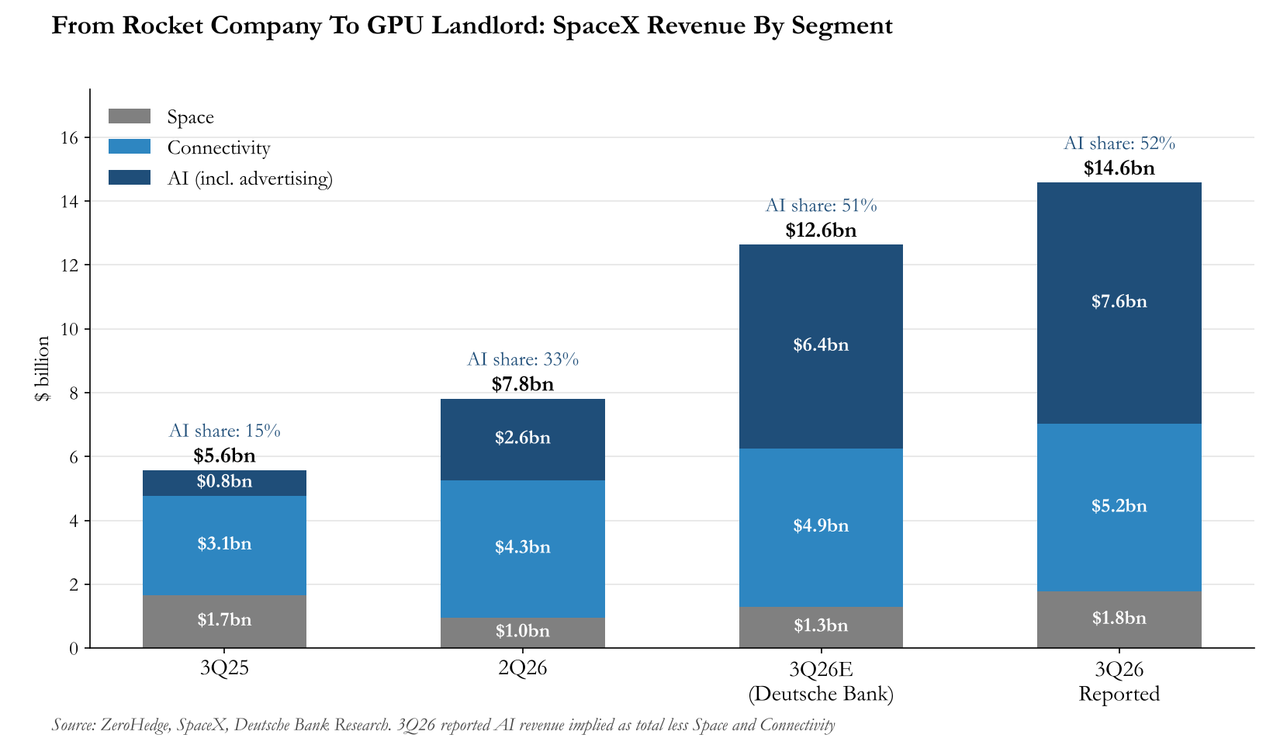
Here is the revenue by segment: it shows that SpaceX is no longer a Rocket Company but is now mostly a neocloud, pardon, Hyperscaler.
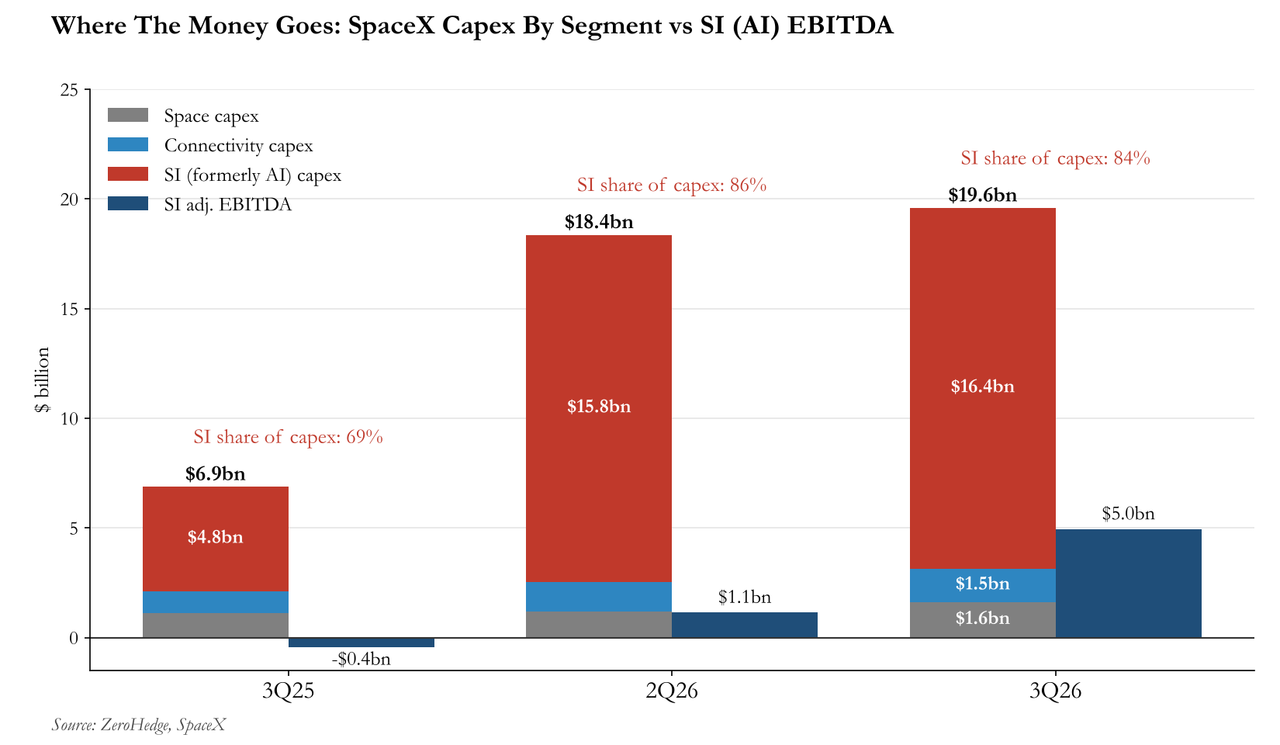
- Capital expenditure $19.59 billion, beating estimates of $19.6 billion
- Space capital expenditure $1.61 billion, higher than estimates of $1.52 billion
- Connectivity capital expenditure $1.54 billion, below estimates of $1.6 billion
Here is the capex by segment:
Turning to expenses…
- Total Costs & Expenses $11.78 billion, beating estimates of $11.23 billion
- R&D expenses $4.60 billion, missing estimates of $5.06 billion
… and operating income:
- Operating income $2.79 billion, beating estimates of $2.24 billion
- Connectivity operating income $2.37 billion, beating estimates of $1.86 billion
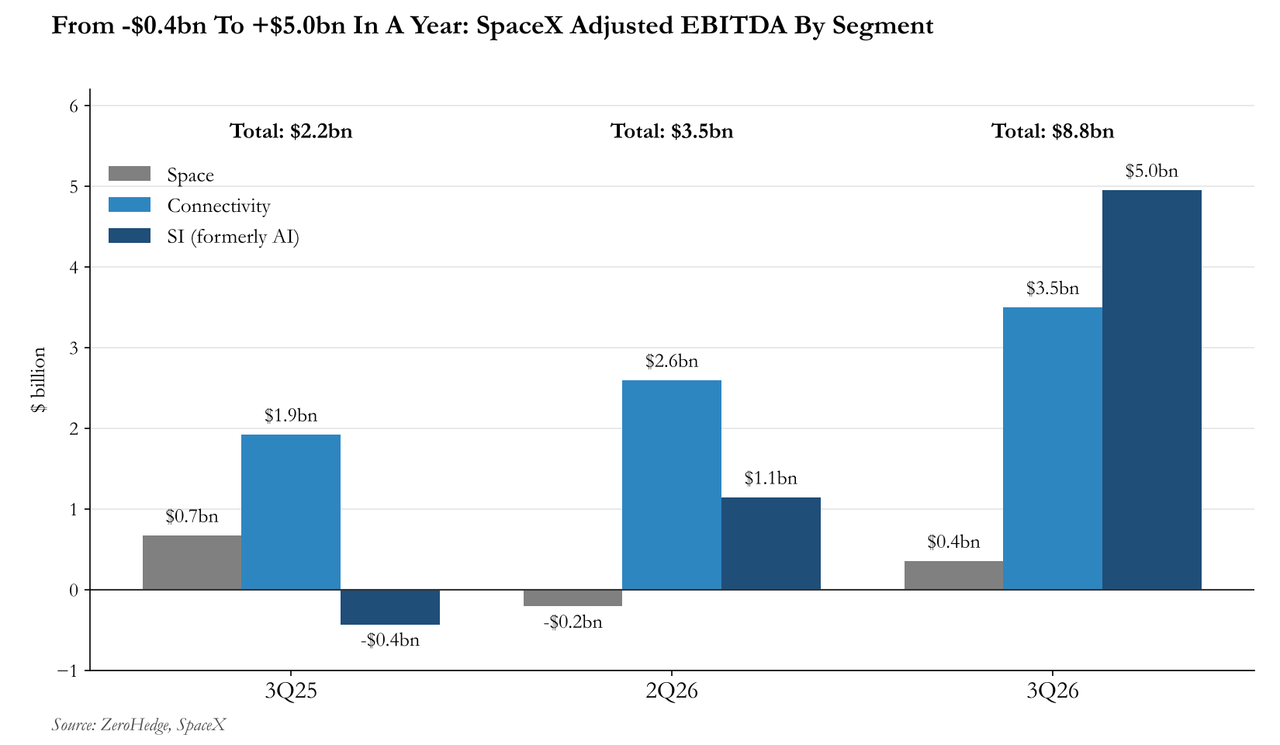
- Adjusted Ebitda $8.81 billion, smashing estimates of $6.59 billion
- Space adjusted Ebitda $357 million, estimate $123.1 million
- Connectivity adjusted Ebitda $3.50 billion, estimate $2.94 billion
Here is the adjusted EBITDA by segment:
- Number of rocket launches 35, missing estimates of 41
- Mass to Orbit 476 mt, missing estimates of 559
- Cash and cash equivalents $51.29 billion, estimate$91.2 billion
While much will be said about the company’s profitability, note that the $4.4 billion of net income got a boost from $1 billion of “other income” and a $390 million tax benefit. That said, the underlying business still beat expectations: operating income was $2.8 billion versus $2.2 billion expected.
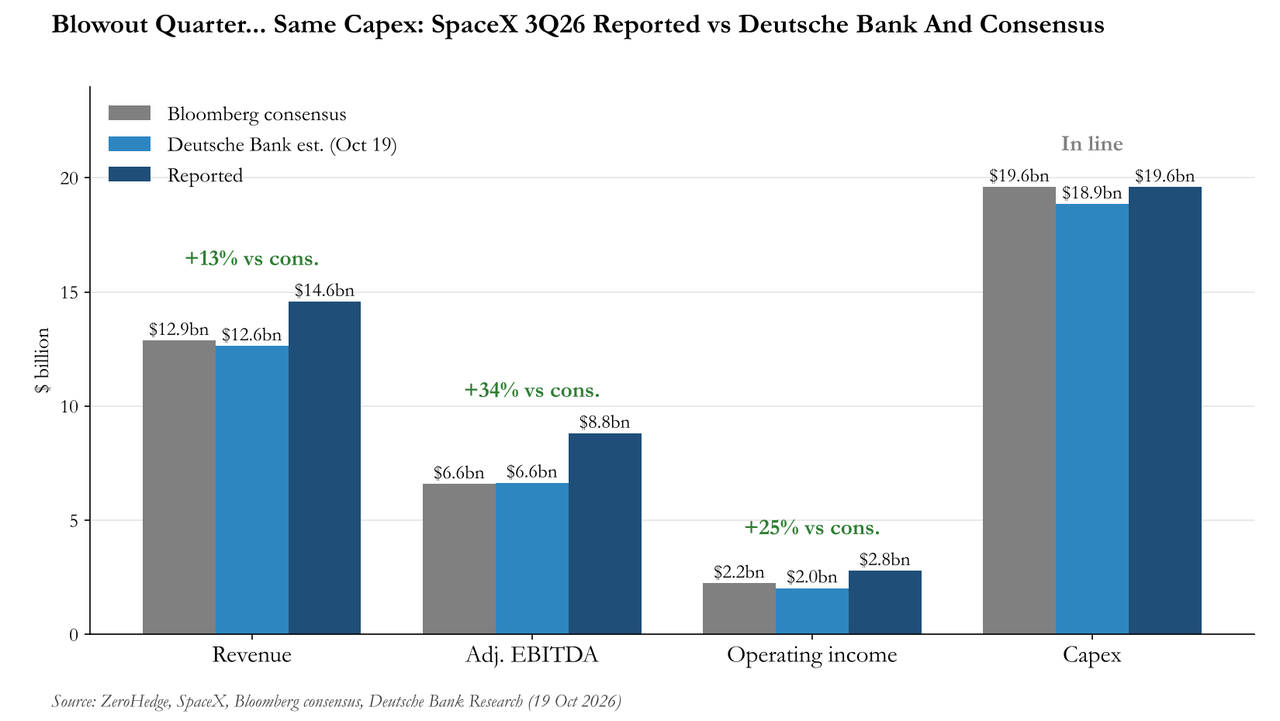
A visual way of representing what happened in Q3:
Looking at the key components, EBITDA and CapEx, we find that both revenue and EBITDA smashed estimates, while CapEx was largely unchanged from last quarter.
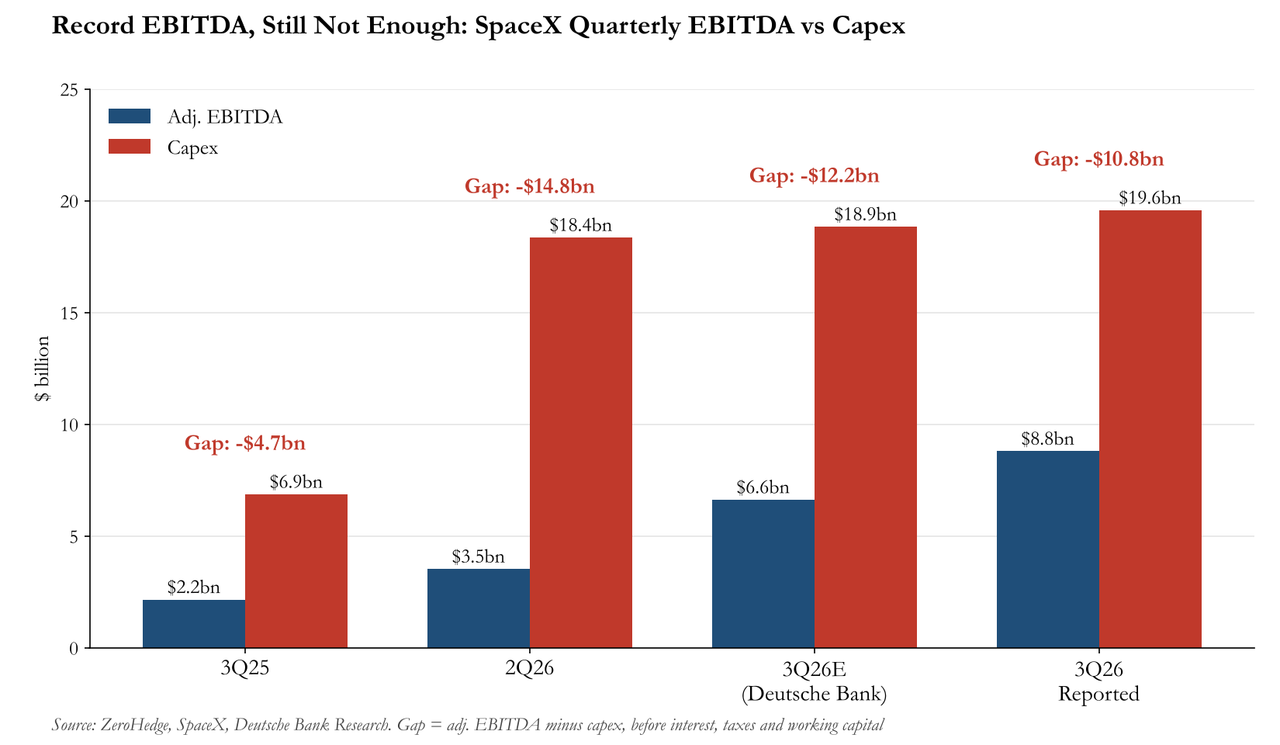
As we noted in our preview the big question would be the delta between EBITDA and CapEx growth, and as shown in the chart below, while EBITDA was a record $8.8BN, it is still nowhere near enough to catch up to the whopping $19.6BN in capex.
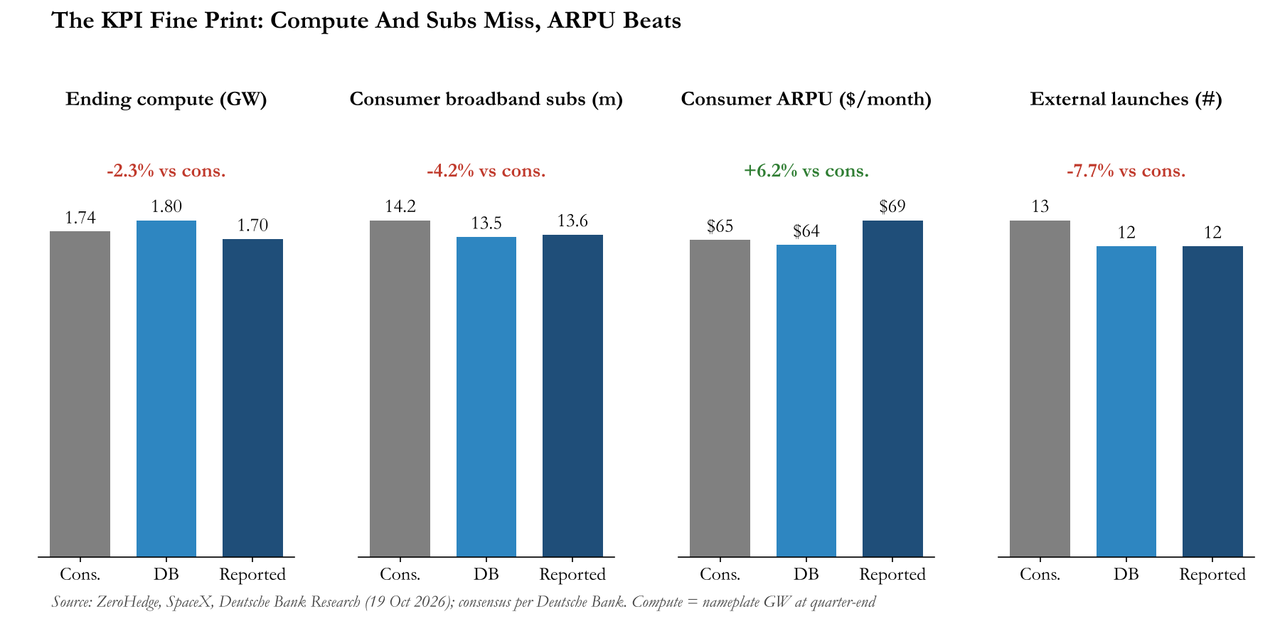
Another very important number: amount of installed compute rose to 1.7GW, just shy of estimates of 1.74GW.
Summarizing the fine print: SpaceX reported blowout revenues and EBITDA, driven by stronger ARPU, even as ending compute, consumer broadband subs and external launches all came below expectations.
Commenting on the quarter, the SpaceX CFO said that the company “delivered another strong quarter in Q3. Revenue grew an impressive 161% year-over-year, fueled by continued momentum in Connectivity and a clear inflection in our Super Intelligence business. The combination of our launch leadership, recurring Starlink revenue, and the significant expansion of our SI infrastructure continues to drive meaningful operating leverage… We are building the infrastructure of the future with discipline — focused on capital efficiency, strong returns on invested capital, and maintaining a robust, investment-grade balance sheet — while moving with the velocity to capture the opportunity in front of us.”
In its wrap, Bloomberg writes that SpaceX of this quarter is not the same as the SpaceX of last quarter. AI – now officially called Super Intelligence – has overtaken Starlink to become the company’s biggest business by revenue. Just last quarter, Starlink was comfortably ahead. The speed of that shift shows just how quickly SpaceX’s AI infrastructure business is scaling.
The SpaceX story used to be rockets funding satellites. Increasingly, it’s rockets, satellites and a giant balance sheet funding an AI company. In other words, a hyperscaler.
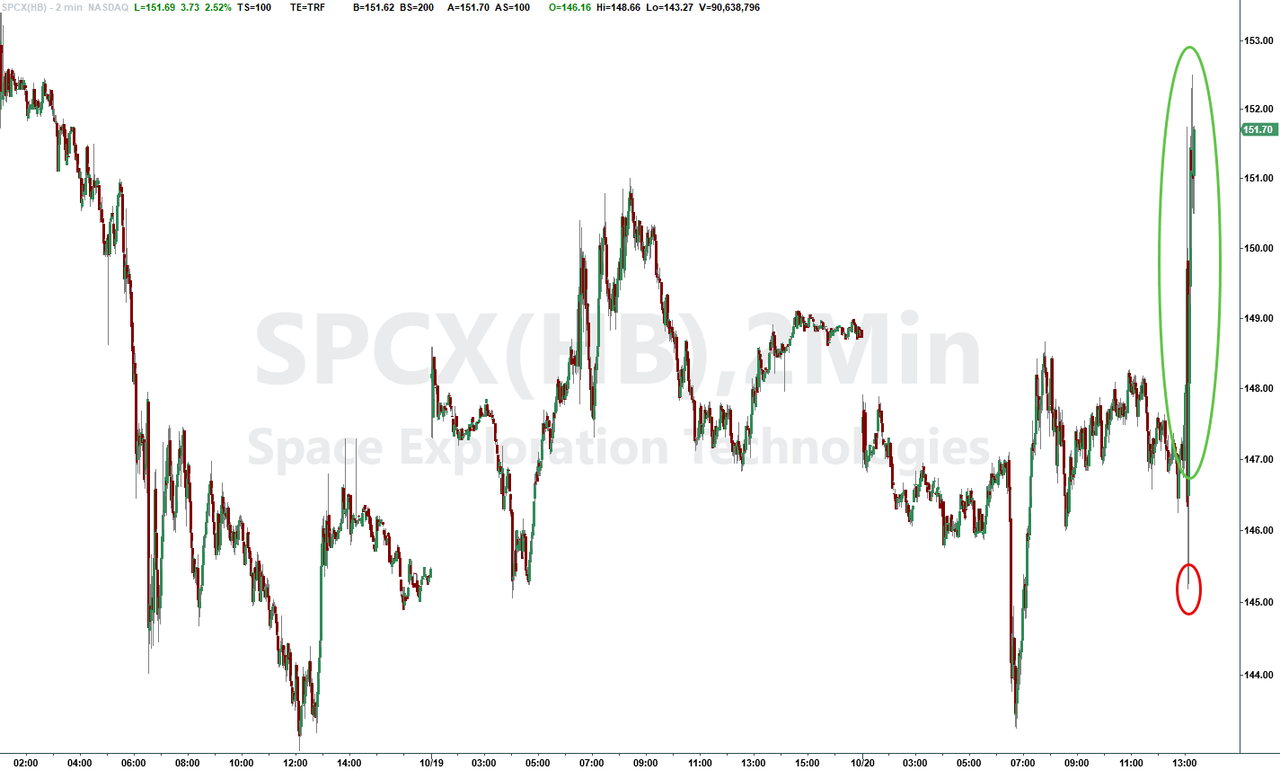
The results were solid, and the stock liked them – at least until the call – with SPCX stock higher about 3%, fading a bit of its after hours jump.
Tyler Durden
Tue, 10/20/2026 – 16:24

