
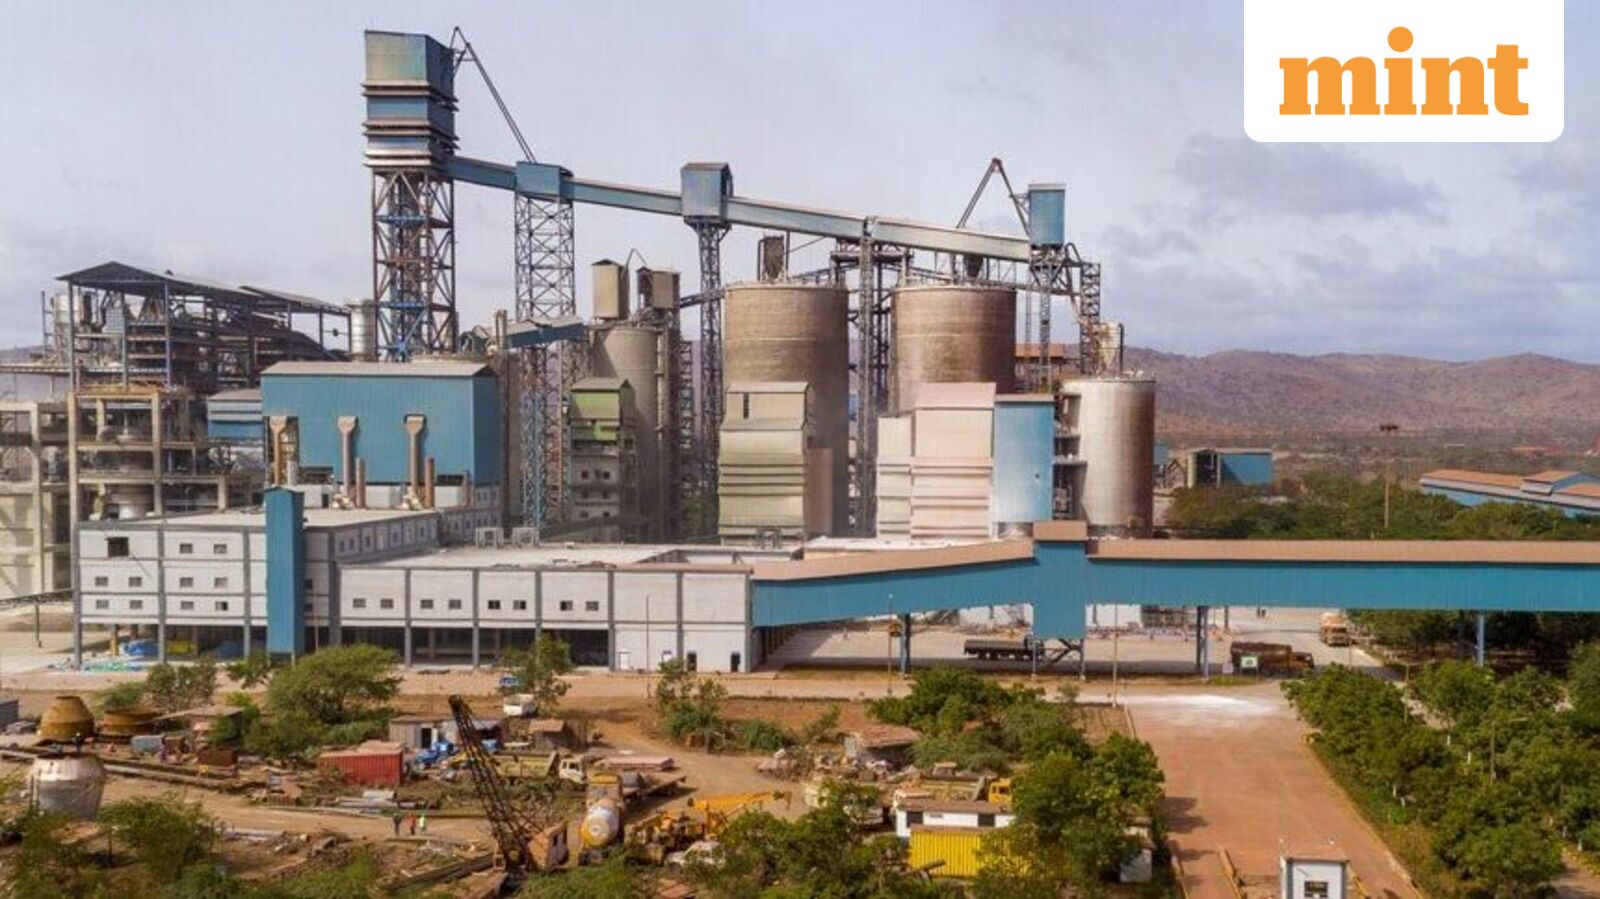
JSW expects volume growth in the high teens in FY27, but costs are a near-term re-rating trigger.JSW expects volume growth in the high teens in FY27, but costs are a near-term re-rating trigger.


Your trusted source for real-time market insights, expert analysis, and breaking financial news. We deliver actionable updates on global markets, stocks, crypto, and economic trends empowering investors to make informed decisions every day.
Contact us: contact@financeworld-news.com
© Copyright 2025 - financeworld-news.com