
Key Events This Week: Trump-Xi Meeting, Fed Speakers, PMIs And Durables
After an extremely busy week for central bank decisions, the week ahead brings a mix of economic data, even more central bank decisions, lots of Fed speak, and geopolitical events.
The first read of the September PMIs across the major economies on Wednesday should provide the most timely update on global growth momentum, while investors will also be watching policy decisions from the Norges Bank, Riksbank and SNB on Thursday with their hike probabilities according to futures at 62%, 21% and 5% respectively, according to Deutsche Bank.
Attention will also turn to the meeting between Presidents Trump and Xi on Thursday which will likely garner a lot of headlines. We also have opening week of the UN General Assembly debate in New York.
In the US, the focus will increasingly shift towards next Friday’s payrolls report, which will be the most important data release before the October FOMC meeting. Ahead of that, markets will be very keen to hear from a heavy schedule of Fed speakers throughout the week. These comments will frame last week’s FOMC meeting, where policymakers delivered a widely expected rate increase but signalled a more hawkish policy outlook. The updated projections showed a strong majority of officials anticipating further tightening, while Chair Warsh emphasized that the Committee still sees limited evidence that policy is meaningfully restrictive.
Fed communication begins today with Chicago Fed President Goolsbee alongside the Chicago Fed National Activity Index. Tomorrow, investors receive the Philadelphia Fed non-manufacturing survey and the Richmond Fed manufacturing index. On the policy front, Fed Vice Chairs Williams and Jefferson are due to speak. Williams is viewed as one of the four officials who are still expected to see the Fed easing by the end of next year, so any hints on that outlook will be closely scrutinized.
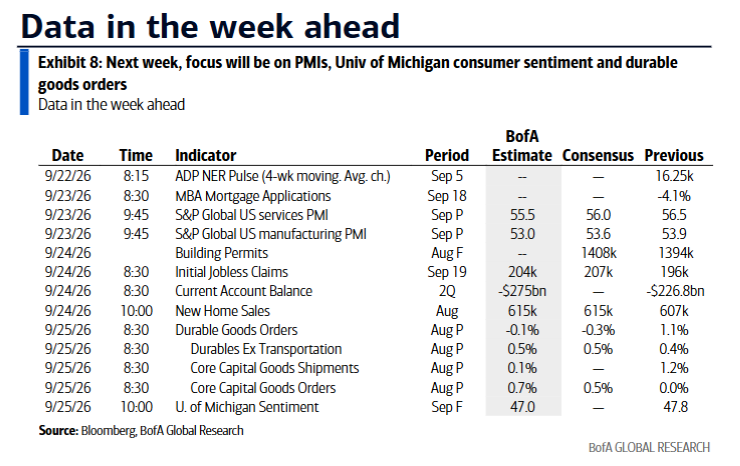
Wednesday’s main event will be the September flash PMIs. Economists expect the US manufacturing PMI to edge down to 53.6 from 53.9, while the services gauge is forecast to ease slightly to 55.9 from 56.5. Given the recent focus on AI-related investment and broader capex trends, these surveys will be watched closely for signs that business activity remains resilient. Fed Governor Barr is also due to speak. Investors will also be watching Wednesday’s Treasury buyback announcement ahead of Thursday’s 20-30yr operation, particularly after last month’s decision to at least double the size of long-end buybacks.
Thursday sees August new home sales and initial jobless claims. Last week continuing claims hit their lowest since January 2024. Fed speakers include Williams, Barkin, Hammack and Paulson, offering further opportunities for markets to assess where officials stand after last week’s hawkish meeting. Friday’s US durable goods report will be particularly important from a growth perspective. Our economists expect headline orders to rise by 0.6% month-on-month, with orders excluding transportation and core capital goods both expected to increase by 1.1%. The data should provide one of the clearest indications yet of whether the recent strength in business investment is being sustained. Williams and Hammack are also due to speak on Friday.
Here is a day-by-day calendar, courtesy of DB
Day-by-day calendar of events
Monday September 21
- Data: US August Chicago Fed national activity index, China 1-yr and 5-yr loan prime rates
- Central banks: Fed’s Goolsbee speaks, ECB’s Kazimir and Dolenc speak, BoC’s Macklem speaks
Tuesday September 22
- Data: US September Philadelphia Fed non-manufacturing activity, Richmond Fed manufacturing index, business conditions, UK August public finances, Eurozone September consumer confidence
- Central banks: Fed’s Williams, Jefferson and Barkin speak, ECB’s Nagel and Sleijpen speak
- Auctions: US 2-yr Notes ($69bn)
- Other: General debate of the UN’s General Assembly in New York (until September 28)
Wednesday September 23
- Data: US, UK, Germany, France and Eurozone September PMIs
- Central banks: Fed’s Barr speaks, ECB’s Vujcic, Zigman and Lane speak
- Auctions: US 2-yr FRN (reopening, $28bn), 5-yr Notes ($70bn)
- Other: OECD’s interim economic outlook
Thursday September 24
- Data: US August new home sales, September Kansas City Fed manufacturing activity, Q2 current account balance, initial jobless claims, Japan September PMIs, Germany September Ifo survey, France September consumer confidence, business confidence, EU27 August new car registrations, Canada July retail sales, Australia labour force survey
- Central banks: Central bank decisions in Norway, Sweden and Switzerland, Fed’s Williams, Barkin, Hammack and Paulson speak, ECB’s economic bulletin, BoE’s Dhingra, Breeden and Lombardelli speak
- Earnings: Costco
- Auctions: US 7-yr Notes ($44bn)
- Other: US President Trump and China’s President Xi meeting in the US
Friday September 25
- Data: US August durable goods orders, September Kansas City Fed services activity, UK September GfK consumer confidence, Germany October GfK consumer confidence, Eurozone August M3
- Central banks: Fed’s Williams and Hammack speak, ECB’s Vujcic speaks
Looking at just the US, The key economic data release this week is the durable goods report on Friday. There are many speaking engagements with Fed officials this week, including events with Governor Barr on Wednesday, President Paulson on Thursday, President Hammack on Thursday and Friday, and President Williams on Tuesday, Thursday, and Friday.
Monday, September 21
- There are no major economic data releases scheduled.
- 06:30 AM Chicago Fed President Goolsbee (FOMC non-voter) speaks: Chicago Fed President Austan Goolsbee will speak about monetary policy at the Official Monetary and Financial Institutions Forum in London. Speech text and Q&A are expected. On August 28, Goolsbee said, “As I look at the inflation data, we were above the target, then it was going the wrong way, then we got a couple of months of more benign readings but that certainly doesn’t feel like we’re out of the woods.”
Tuesday, September 22
- There are no major economic data releases scheduled.
- 10:05 AM New York Fed President Williams speaks: New York Fed President John Williams will give keynote remarks during the New York Fed’s Treasury Market Conference. Speech text is expected. On September 2, Williams explained that “we are neither seeing second-round effects, nor unusual broadening of the effects of higher energy prices, and we are seeing well anchored inflation expectations,” though his comments came prior to September’s warmer CPI print.
- 10:20 AM Fed Vice Chair Philip Jefferson speaks: Fed Vice Chair Philip Jefferson will speak at the New York Fed’s Treasury Market Conference on discount window modernization and Treasury market functioning. Speech text is expected.
- 01:00 PM Richmond Fed President Barkin (FOMC non-voter) speaks: Richmond Fed President Tom Barkin will deliver a speech to the CFA Society Baltimore. Speech text and Q&A are expected.
Wednesday, September 23
- 09:45 AM S&P Global US manufacturing PMI, September preliminary (consensus 53.5, last 53.9); S&P Global US services PMI, September preliminary (consensus 56.0, last 56.5)
- 10:05 AM Fed Governor Barr speaks: Fed Governor Michael Barr will speak on housing at the Chicago Fed Community Development Summit. Speech text and Q&A are expected. On September 1, Barr said, “A series of shocks—from tariffs and then the conflict in the Middle East, as well as from the rapid AI buildout—has pushed us off course. And core non-housing services inflation remains elevated.” He also added that “with inflation above target for a protracted period, there is a risk of broader price pressures taking hold, a risk I am watching closely.”
Thursday, September 24
- 04:10 AM New York Fed President Williams speaks: New York Fed President John Williams will participate in a moderated discussion during the London Macro Policy Forum. Q&A is expected.
- 08:00 AM Richmond Fed President Barkin (FOMC non-voter) speaks: Richmond Fed President Tom Barkin will participate in a fireside chat at The Economic Club of Washington D.C. Q&A is expected.
- 08:30 AM Initial jobless claims, week ended September 19 (GS 200k, consensus 200k, last 196k): Continuing jobless claims, week ended September 12 (consensus 1,750k, last 1,730k)
- 08:50 AM Cleveland Fed President Hammack (FOMC voter) speaks: Cleveland Fed President Beth Hammack will give opening remarks at the Inflation: Drivers and Dynamics Conference hosted by the Cleveland Fed and the European Central Bank. Speech text is expected. On September 4, Hammack stated, “Both the hard data and the anecdotes are telling me the same thing: policy is not restrictive. Inflation is too high—and the longer it stays above our objective, the harder it will be to bring it back down…Right now, what I’m hearing is that it is time to act.”
- 10:00 AM New home sales, August (GS +0.7%, consensus +1.3%, last -10.5%)
- 10:10 AM Philadelphia Fed President Paulson (FOMC voter) speaks: Philadelphia Fed President Anna Paulson will speak about the economic outlook at the Tenth Annual Fintech Conference hosted by the Philadelphia Fed. Speech text is expected. On August 4, Paulson explained that she sees “two plausible scenarios for how current policy is affecting inflation.” One is that “the current setting of the federal funds rate is mildly restrictive and this will bring inflation to 2 percent in an acceptable time frame” and the other is that “current policy is not restrictive enough to deliver our target rate of 2 percent inflation.”
Friday, September 25
- 05:15 AM New York Fed President Williams speaks: New York Fed President Williams will participate in a policy panel during the 6th Monetary Economics Conference in Oxford, UK. Q&A is expected.
- 08:30 AM Durable goods orders, August preliminary (GS -1.0%, consensus -0.3%, last +1.1%); Durable goods orders ex-transportation, August preliminary (GS +0.6%, consensus +0.6%, last +0.4%); Core capital goods orders, August preliminary (GS +0.5%, consensus +0.7%, last flat); Core capital goods shipments, August preliminary (GS +0.3%, consensus +0.7%, last +1.2%): We estimate that durable goods orders declined 1.0% in the preliminary August report (month-over-month, seasonally adjusted) based on our tracking of commercial aircraft orders. We forecast a 0.5% increase in core capital goods orders—reflecting continued strength in the new orders components of manufacturing surveys in August—and a 0.3% increase in core capital goods shipments—reflecting the continued increase in core capital goods orders in recent months.
- 10:00 AM University of Michigan consumer sentiment, September final (GS 47.5, consensus 47.5, last 47.8): University of Michigan 5-10-year inflation expectations, September final (GS 3.4%, last 3.4%)
- 2:00 PM Cleveland Fed President Hammack (FOMC voter) speaks: Cleveland Fed President Beth Hammack will participate in a policy panel discussion at the Inflation: Drivers and Dynamics Conference hosted by the Cleveland Fed and the European Central Bank. Q&A is expected.
Source: DB, Goldman
Tyler Durden
Mon, 09/21/2026 – 10:55

