
Futures Drop, Yields And Oil Jump Ahead Of Iran’s UN Address As Trump-Xi Summit Looms
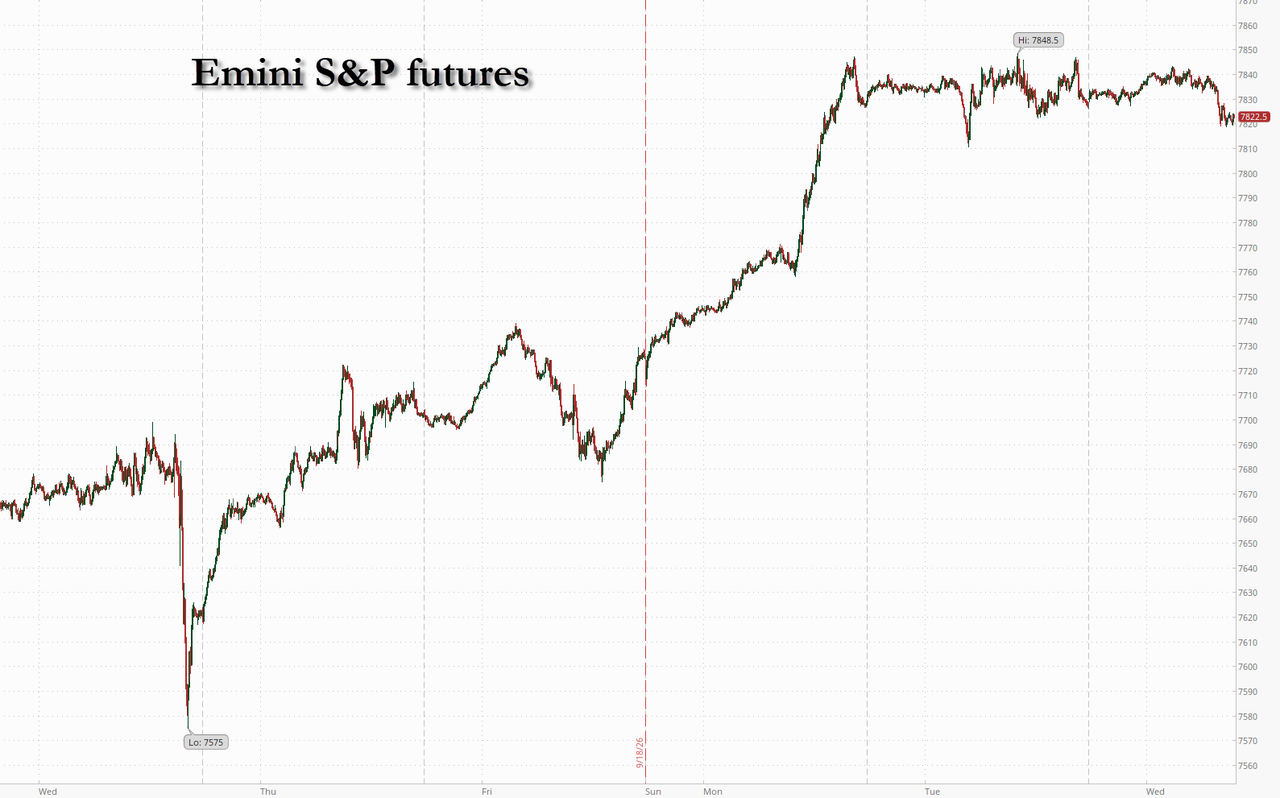
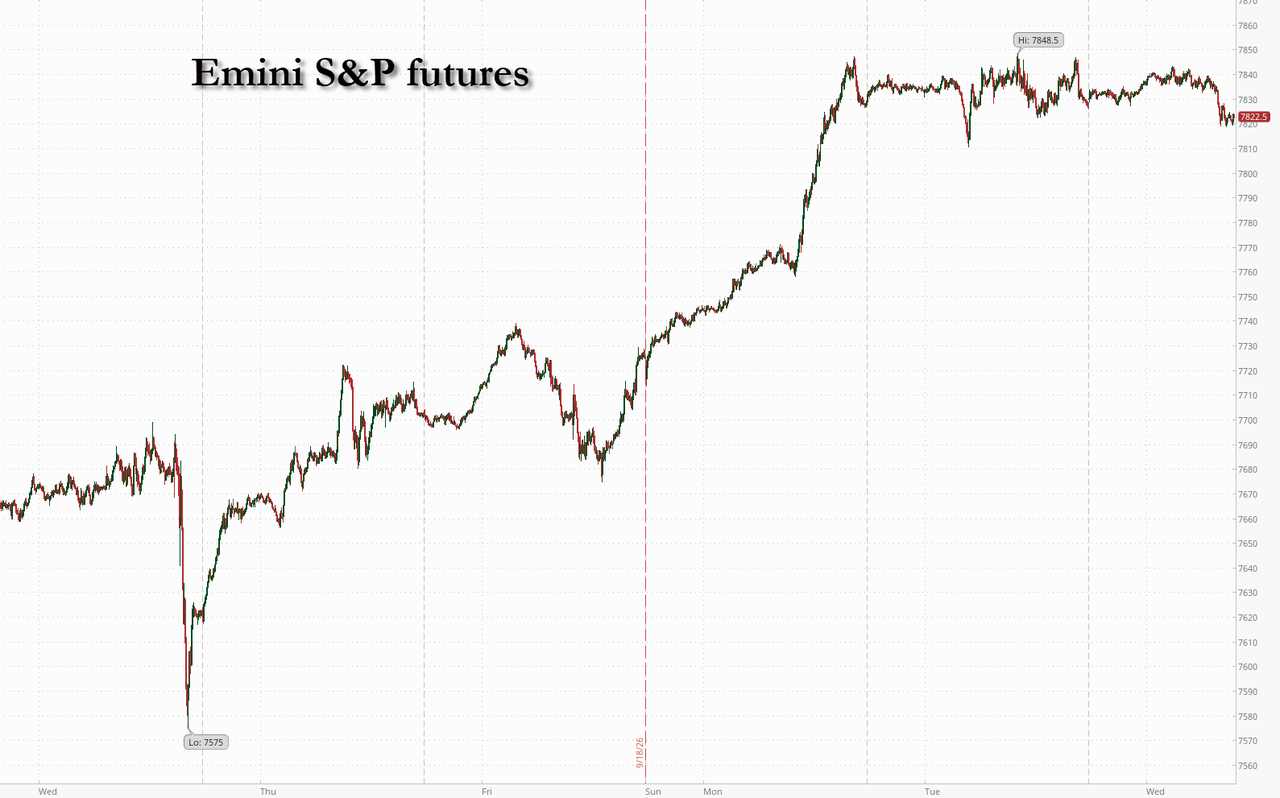
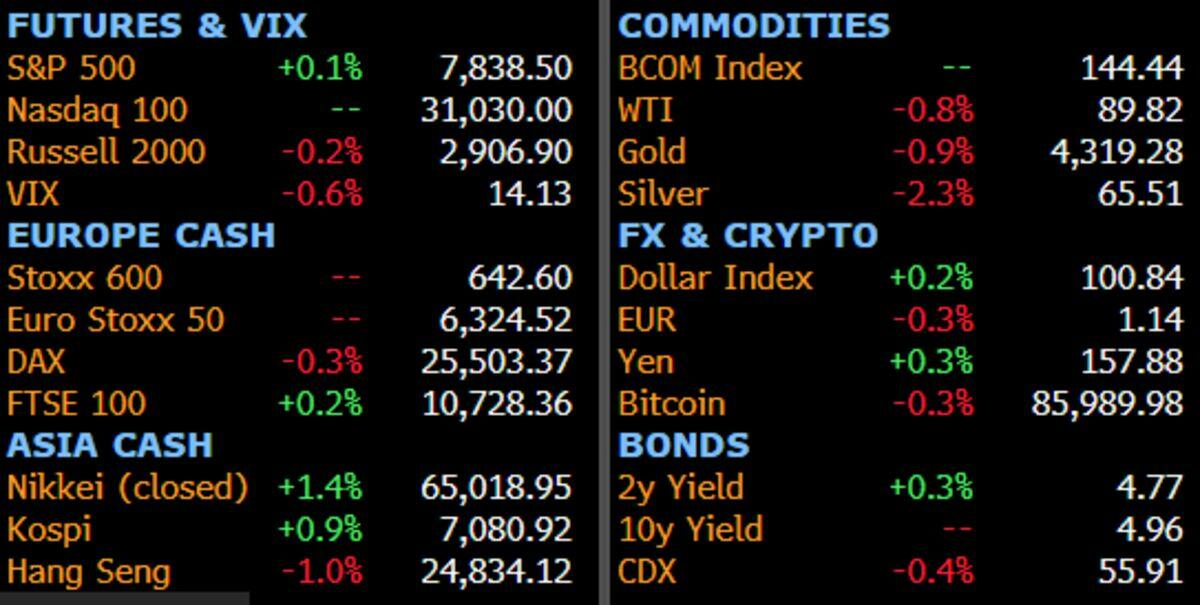
US equity futures are down modestly, but at session lows, as oil reverses earlier losses (crude was on pace for a sixth straight day of declines, its longest losing run in a year) sending Brent back over $100 and pushing 10Y yields back to 4.99%. As of 8:30am, S&P 500 futures were 0.1% lower with Nasdaq 100 futures sliding 0.3%, and also at session lows after hitting a record on Tuesday. In premarket trading, memory and semis are lower as Mag7/software are higher. Within SPX sectors, all of the majors have pockets of strength ex-Materials which are set to lag given the sell off in metals. Rising oil prices have also weighed on European equities, which have pared opening gains and left the Stoxx 600 down 0.5%, also at session lows. In Asia, Chinese and Hong Kong shares declined, trailing regional peers including South Korean and Taiwanese benchmarks. Oil remains the wildcard for stocks and bonds, while Meta’s Muse AI agent is reshaping sector rotation. Yields are notably higher, with 2Y yields rising to a 2 year high of 4.79% as the curve flattens aggressively, as the tactical market narrative seeks more color from UN meetings (US/China; US/Iran; NATO+UKR/Russia) before deciding direction. The USD rally continues with the DXY 75bp away from YTD highs set June 24. Commodities are lower ex-Energy which is seeing a bid within fuels / natgas and Brent is outperforming WTI. Base over Precious and Ags uniformly sold. The US economic calendar includes September S&P Global US manufacturing and services PMIs at 9:45 a.m. Fed speaker slate includes Governor Barr (10:05 a.m.) and Chicago’s Goolsbee (12 p.m.)
In premarket trading, Mag 7 names are mostly higher: Microsoft received a bullish upgrade from Stifel, which writes that the software giant is “getting back on track.” Shares of Microsoft (MSFT) are up 0.9%. Meta +0.3%, Amazon +0.2%, Alphabet +0.1%, Tesla -0.2%, Apple +0.2%, Nvidia -0.4%
- Cracker Barrel (CBRL) climbs 8% after the restaurant operator reported adjusted earnings per share for the fourth quarter that beat the average analyst estimate.
- IonQ (IONQ) rises 11% after the quantum computing company said it developed the tech industry’s first end-to-end real-time quantum error correction decoder that runs on a single standard off-the-shelf central processing unit.
- Voyager Technologies (VOYG) falls 7% after the space and defense company announced its intention to offer $350 million of convertible senior notes in a private offering.
- Worthington Enterprises (WOR) jumps 16% after the maker of aluminum propane cylinders posted fiscal first quarter earnings and revenue that topped expectations, helped by acquisitions and a tariff refund.
In other corporate news, Six Flags Entertainment shares gain in premarket trading as the Wall Street Journal reports that activist hedge fund Jana Partners is urging the theme-park operator to explore a sale. China’s State-owned Assets Supervision and Administration Commission has been surveying the number of Broadcom switches in state-controlled data centres in recent weeks, the FT reports. The Boeing engineers union recommended the company’s latest contract offer.
While stocks are drifting lower, there is little urgency to the move. A packed agenda could quickly shake futures out of their early lull. As Bloomberg notes, “Investors look ready to re-risk, after the vol-of-vol gauge touched its lowest since December 2024”, however potential geopolitical hurdles, not to mention very sticky high diesel and oil prices, remain. Iranian President Masoud Pezeshkian addresses the UN General Assembly Wednesday.
Geopolitics remain center stage as traders look to a resolution in the Middle East as a catalyst that could pave the way for lower inflation and a brighter growth outlook. President Donald Trump flagged progress in US talks with Iran even after threatening to annihilate the Islamic Republic. Trump said US officials had “very good” talks with Iranian envoys, with another round being planned for the near future. Iran has yet to comment on the meeting. Meanwhile, Saudi Arabia moved to restart a key pipeline.
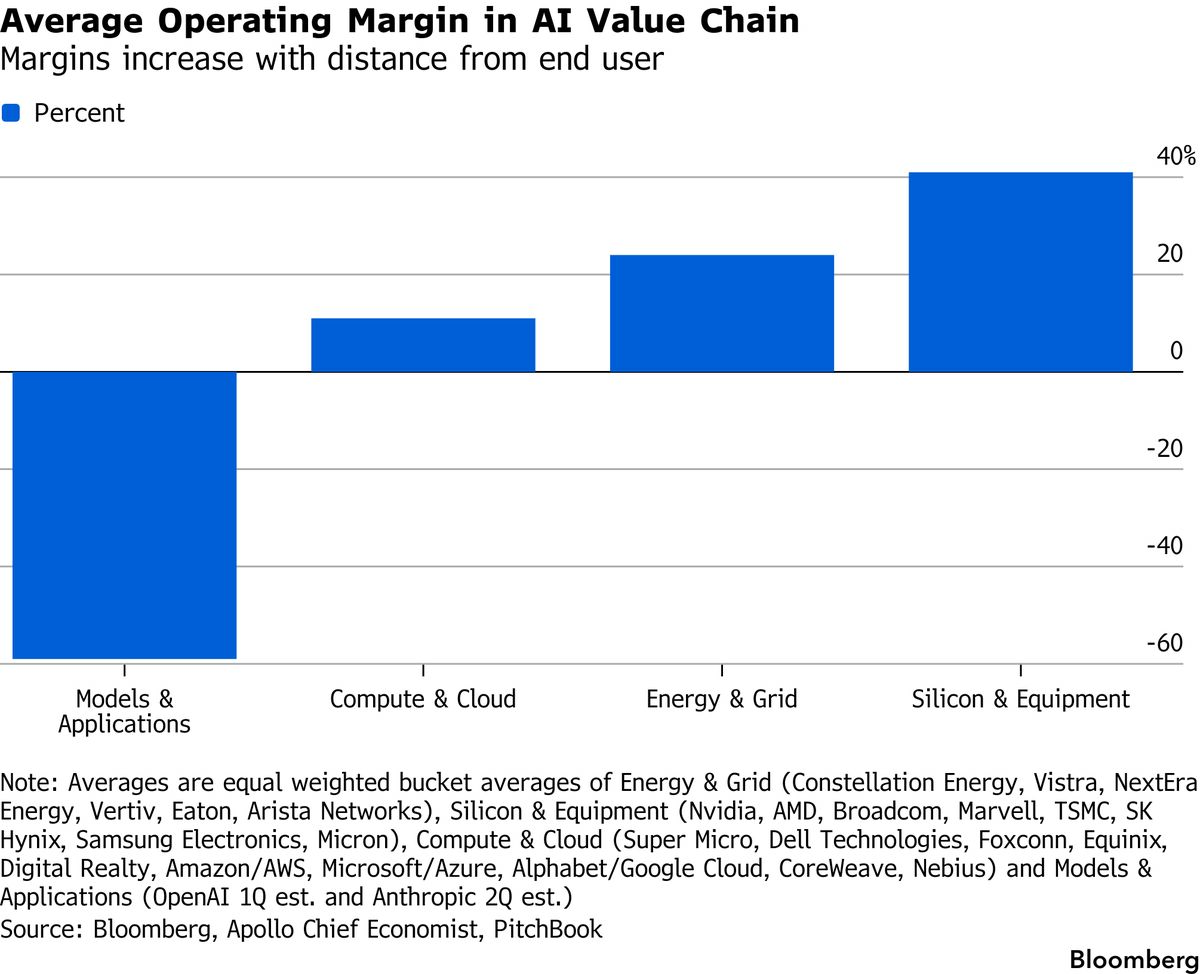
The Tech-heavy Nasdaq 100 hit a fresh record high Tuesday, while financials closed at their lowest since July on fears that tools such as Meta’s Muse personal AI agent could disrupt businesses that benefit from consumer inertia. That puts Zuckerberg’s keynote scheduled for tonight firmly on investors’ radar. Profit margins are frequently higher for the owner of the end-customer relationship, as Apple has shown with the iPhone. The key question is whether Muse can shift AI economics in that direction: will companies deploying AI generate returns quickly enough to sustain the spending that is currently driving margins further up the supply chain?
“Risk sentiment in equities, but also the outlook for interest rates and inflation is going to trade a lot around expectations and movements in the oil price,” said Emma Moriarty at CG Asset Management. “Brent has fallen, but the overall level is still very high and it probably needs to go some way further.”
Elsewhere in tech, Softbank is offering record yields on what’s set to be one of the largest corporate junk bond sales ever. Meanwhile, Chinese AI model developer stocks fell after a report that the country’s regulators have opened a probe into startups DeepSeek and Moonshot AI over data security concerns. Today’s Tech Watch looks at how China’s AI trade favors global winners over local champions.
Traders are also looking to the summit between Trump and China’s Xi Jinping later this week for signs of progress on trade and other economic issues. Trump is welcoming Xi to Washington today for a visit focused more on pageantry than policy, with low expectations for breakthroughs on long-standing disputes. The highly anticipated summit will bring together a robust gathering of US corporate leaders, including Mark Zuckerberg, Jensen Huang, and Elon Musk, among others, but no comparable delegation of Chinese executives.
“Neither side looks ready to fundamentally reset the trade relationship, with the threats of restricting critical mineral exports countering the US administration’s desire to turn back to tariffs,” wrote Robert Gilhooly, senior emerging markets economist at Aberdeen Investments.
Preliminary bilateral talks in New York on Sunday were hailed as positive, but failed to reach an agreement on extending a tariff truce expiring in November. “Investors are zeroing in on what’s going to move markets and that’s the coming peace talks and the Xi/Trump summit,” said Josh Gilbert, lead APAC analyst at Etoro. “With Trump, we know that headlines can change on a dime, so there’s a level of taking some risk off the table.”
In politics, fractures within the GOP have widened into open rifts as Trump’s popularity sinks to new polling lows, just six weeks until US midterm elections. The DoJ urged a federal judge to reject a request by CNN, MS Now and Politico for a court order reinstating White House press credentials for their journalists.
In other assets, Apollo is limiting redemptions from a private credit fund for the third straight quarter, as its investors join the rush to pull cash from the $1.8 trillion direct lending market. High-grade data-center bonds offer some of the most compelling investment opportunities in credit, according to CVC Marathon CEO.
SoftBank kicked off what could be one of the largest corporate junk bond sales ever, with the group aiming to raise the equivalent of more than $11 billion. Meantime, Alibaba is accelerating its data center expansion in Europe and the Middle East.
In a week where the economic data calendar is relatively sparse, S&P Global is releasing its preliminary September manufacturing and services purchasing managers’ indexes on Wednesday. For the US, both readings are projected to remain consistent with steady growth.
Rising oil prices also weighed on European equities, which have pared opening gains and left the Stoxx 600 down 0.5% also at session lows, despite better-than-expected PMI data against a backdrop of geopolitical uncertainty. Banks and financial services outperform, insurance and real estate fall. Here are some of the biggest movers on Wednesday:
- Raiffeisen shares gain as much as 4.2% after a Vienna court issued a default judgment against Rasperia Trading, ordering damages of about €3.15b.
- Lakefront Biotherapeutics shares rise as much as 5.4% after analysts at RBC Capital Markets upgraded their view on the company’s ADRs, saying its potential in rare autoimmune diseases is “underappreciated by investors.”
- Renishaw shares rise as much as 4.5% after the electronic components maker reported profits slightly ahead its post-close update and said it will pay a special dividend.
- EFG International shares rise as much as 6.4% after the Swiss private bank settled a legal case and said it sees additional costs of 5 million Swiss francs.
- Arcadis falls as much as 11% in Amsterdam after WSP Global says it won’t pursue a public offer for the engineering consultancy and services firm.
- Grenergy Renovables slides as much as 8.8% as RBC lowers its price target on the stock, saying heavy asset rotation is pressuring the Spanish renewables company’s earnings.
- Ceres Power shares fall as much as 7.2% after the British fuel cell developer reported revenue for the first half-year that missed the average analyst estimate.
- Diageo hares fall as much as 1.6% after the drinkmaker announced a new chief financial officer.
- Sampo shares fall as much as 3.4% after an offering of 70m Class A shares by holder Solidium priced at a 2.8% discount to prior close.
- JD Sports shares drop as much as 2.2% after the sports retailer reported first-half results that Shore Capital said confirmed a challenging trading period.
Asian equities pared gains on caution ahead of President Donald Trump’s highly anticipated summit with China’s Xi Jinping, while Chinese tech selling tempered advances in regional chip stocks. The MSCI Asia Pacific ex-Japan Index rose as much as 0.8% before paring its increase to 0.2%. Tencent and Alibaba fell in Hong Kong as Chinese tech shares came under pressure following a report of a government probe into data security at large-language-model developers DeepSeek and Moonshot. The Asian guage is still on track to eke out gains for a sixth day, its longest winning streak in five weeks. Trump and Xi will meet in Washington this week, but expectations are low for breakthroughs on long-standing feuds between the world’s biggest economies. Preliminary bilateral talks in New York on Sunday were hailed as positive, but failed to reach an agreement on extending a tariff truce expiring in November. South Korea’s Kospi Index was up 0.5% after initially surging 1.9%. Stocks also rose in Taiwan and Indonesia. Japan remains shut for a holiday, with markets set to open on Thursday.
“The focus is turning to the huge geopolitical risk event that is Xi meeting Trump in Washington – could split either way with a fresh trade truce or could see some fresh signs of friction,” Neil Wilson, a strategist at Saxo, wrote in a note. “I don’t think there is going to be some grand bargain emerging from this summit but warm words and good vibes might be sufficient given the bullishness around AI and signs of progress with the US-Iran war.”
In FX, the Bloomberg Dollar Spot Index is extending gains, advanced 0.4% in fourth straight day of gains to levels not seen since late July. The currency has shown resilience in the face of lower energy prices as Federal Reserve officials continue to stress the need for policy vigilance after last week’s US interest-rate hike. Fed Governor Michael Barr and Chicago Fed President Austan Goolsbee are scheduled to speak later Wednesday.
US yields are up 2bps at the front-end and flat across the rest of the curve. Front-end EGB yields have been supported by a solid set of euro-area PMI data, leaving the economic “resilience” narrative intact and the ECB priced for further hikes. UK PMIs were comparably weaker but not enough to dent expectations of a BOE increase in November, which have been providing a floor under front-end yields amid this week’s decline in energy prices.
In commodities, brent crude is flat, having reversed overnight declines, leaving it on track to snap its recent streak of losses. The firmer greenback is placing a squeeze on precious metals, with spot gold down about 1% and silver lower by 2.5%. Bitcoin sheds 0.4%.
In rates, treasuries are narrowly mixed in early US trading, with European bonds lagging after German and French PMI gauges topped forecasts. US yields are within a basis point of Tuesday’s closing levels, the 10-year around 4.96%, outperforming bunds and gilts in the sector by 1.5bp and 0.5bp respectively. Treasury auction cycle continues with $70 billion of 5-year notes at 1 p.m. New York time and concludes Thursday with $44 billion 7-year; Tuesday’s $69 billion 2-year note tailed narrowly. WI 5-year yield near 4.845% is ~45bp cheaper than last month’s auction, which tailed by 0.2bp, the tenor’s ninth consecutive tail. IG dollar issuance slate includes a couple offerings so far; eight were priced Tuesday totaling $18.2 billion, with issuers paying 1bp in new issue concession on deals that were 5 times covered. US manufacturing and services PMIs are ahead Wednesday, along with a 5-year note auction.
In commodities, oil prices have swung between gains and losses as Saudi Arabia moved to restart its East-West pipeline link to the Red Sea by Saturday, while the US flagged progress in talks with Iran to end a war that has disrupted energy markets.
The US economic calendar includes September S&P Global US manufacturing and services PMIs at 9:45 a.m. Fed speaker slate includes Governor Barr (10:05 a.m.) and Chicago’s Goolsbee (12 p.m.)
Market Snapshot
Top Overnight News
- Oil wavered as Brent headed for its longest losing streak in more than a year on hopes for progress in US-Iran talks and higher supplies. Iran said about half of war-hit South Pars’ gas capacity is back online, Fars reported. BBG
- Trump on Tuesday said he backed the idea of a diesel export ban as a way to lower prices that have hit record highs due to a global supply shortage. But analysts and market watchers warn that such a measure would do little to ease high energy prices, and could worsen supply and economic disruptions around the globe. RTRS
- Xi Jinping arrives for a state visit today, with Trump hosting a roster of US corporate leaders but no comparable Chinese business delegation is expected, clouding deal prospects, a senior US official said. The two may find common ground on AI safety, but neither is willing to give ground in the technology race. BBG
- Chinese authorities are examining the use of Broadcom’s hardware in state-backed data centers amid a drive to boost domestic producers and reduce reliance on foreign AI infrastructure. FT
- The US and South Korea are set to unveil an agreement for Seoul to fund a multibillion-dollar gas-fired power plant in Texas, the first project under its $350bn investment deal with the Trump administration, according to people familiar with the matter in Washington and Seoul. FT
- The cost of hiring an oil supertanker has passed $1.2mn a day for the first time on routes between the Middle East and Asia, adding to the spiralling pressure on global energy markets triggered by the war in Iran. FT
- Euro-zone private-sector activity grew at the fastest pace in more than three years as the service sector unexpectedly improved. The Composite PMI increased to 53.1 from 52 in August after both Germany and France exceeded forecasts. BBG
- The Treasury’s cash balance topped $1 trillion for the second time in a month as officials study investing excess funds in repo. BBG
- NY Fed’s Perli said Fed’s Reserve Management purchases are not on a pre-set course and that the central clearing of Fed repo operations would have benefits, while Perli added that the monetary policy toolkit has been working well and the Fed’s reserve forecasting process is robust.
- Punchbowl, citing US lawmakers/advisers, outlined that “the electoral climate for President Donald Trump and Republican leaders have worsened dramatically” over the last few weeks.
- US Democratic Senators are introducing a bill to allow first-time homebuyers to get up to USD 50k for a house down-payment: Axios.
- Novo is open to replacing its ADRs with a direct NYSE listing to raise its profile in the US. FT
A more detailed look at global markets courtesy of Newsquawk
APAC stocks were ultimately mixed following the similar handover from the US, despite the recent decline in oil prices and optimism regarding diplomacy after US President Trump announced that envoys had a ‘very productive’ meeting with the Iranian delegation on the sidelines of the UN General Assembly. However, he also threatened that they may have to blow up Pickaxe Mountain and will attack if they see activity, as well as commented that he has a big decision to make between allowing Iran to rebuild or to “annihilate” Iran. ASX 200 was rangebound with demand contained amid rate hike expectations and following weaker Flash PMI data from Australia, in which headline Manufacturing PMI slipped into contraction territory. KOSPI gained after the tech-related momentum in the US, where the NDX printed an all-time high. Hang Seng and Shanghai Comp were subdued following today’s PBoC liquidity drain and as reports that Chinese President Xi is unlikely to bring Chinese CEOs to his summit with US President Trump temper expectations for major business deals.
Top Asian News
- Hong Kong Finance Secretary Chan affirmed no intention to change HKD peg to USD, adding that Hong Kong will remain an open and free economy, while fixed income will be a very big part of Hong Kong.
- Japan’s PM Takaichi said she agreed with US President Trump regarding further strengthening economic security ties and notes the desire for Japan to host an AI summit, while she is pursuing an ever close alliance with the US.
European bourses (STOXX 600 -0.1%) initially started Wednesday’s trading session entirely in the green but have pared slightly, now pointing to a mixed picture. Traders note the widening of London gasoil/NY Heating Oil spread as a catalyst for the pullback in equities, after US President Trump said he would back a pause to American diesel exports. European gas prices are expected to rise and, as a result, weigh on margins as costs increase.
Sectors lack a clear bias, with breadth quite narrow. Banks top the sector pile, with Financial Services and Energy rounding out the sector gainers. To the downside is Insurance, with Real Estate and Telecoms following closely behind.
Top European News
- OECD 2026 GDP Forecasts: US 2.2% (prev. 2.0%), China 4.5% (prev. 4.5%), EU 1.0% (prev. 0.8%), UK 1.1% (prev. 0.9%), World 2.9% (prev. 2.8%).
- Global banking executives warned against a UK windfall tax and that they will divert investment away from the UK if taxes on the sector are raised, according to FT.
- The European Commission proposed lifting 2022 rule of law protective measures against Hungary, seeking to unlock EUR 4.2 bln in suspended cohesion funding and restore access to Erasmus+ and Horizon Europe.
- The German Finance Ministry is reportedly considering a review of takeover law, with reference to “lowball” or “dumping” offers, according to Handelsblatt.
- Germany’s IG Metall said they demand a 5% pay increase in the electrical sector, with regional talks to start on October 7th and warns of possible strikes from November 1st.
- The Swiss Upper House backed the 90% CET1 foreign unit backing by UBS (UBSG SW).
- Italy reportedly plans to stick with its commitment to keep deficit beneath the EU’s 3% GDP ceiling this year, according to sources.
FX
- G10s are lower against the USD to varying degrees. USD continues to digest expectations of a more hawkish Fed, with the likes of Barkin and Collins putting forward their openness to further hikes. This is reflected in the US 2s10s spread, which has been widening for several sessions now. However, the spread is tightening a touch this morning, with focus on Trump suggesting that he would back a diesel export ban. This would no doubt put pressure on domestic prices in the US, whilst simultaneously lifting prices globally, and hence explains some of the downbeat action seen across G10 peers this morning. DXY currently trades at the upper end of a 100.54 to 100.89 range, and is now heading back to levels not seen since late July.
- The Antipodeans underperform this morning, conforming to the negative risk tone. The EUR appears to be faring a touch better vs peers, but still remains in the red. PMI metrics this morning from France and Germany continue to indicate a resilient European economy, despite the Iran war. The French PMI report highlighted that “The pick-up in the PMI price measures seen in September should, however, be watched closely, particularly as we approach the winter months, as the risk of energy price inflation spreading to other areas of the economy undoubtedly rises”. The EZ-wide report was similarly strong, with the inner report suggesting that the mixture of higher growth and rising inflation could embolden the ECB to hike once again this year.
Fixed Income
- A firmer start for fixed income given the overnight energy moderation after the broadly constructive US-Iran update has given way to mixed performance but with a clear negative skew as WTI and Brent pick up alongside increasing focus on product prices/spreads after US President Trump’s comments regarding a diesel ban; see the Commodity-focused update for more detail.
- Initially, USTs got to a 106-08+ peak with gains of c. seven ticks. Since then, the benchmark has faded to near-enough unchanged over the European morning, hit by the mentioned energy upside as we digest Trump’s commentary and also unverified reports of explosions in the Strait of Hormuz.
- Within Europe, the action and drivers have been the same. Bunds got to an early 121.38 peak, firmer by near 20 ticks, before falling into the red by around half of that and losing the 121.00 handle. Adding to this is a generally strong set of EZ Flash PMIs, though German & French Manufacturing were weak. Further, the series also spoke to fresh inflationary pressures; points that have added to the bearish skew in recent trade.
- Gilts opened with modest gains and then climbed to an 86.04 peak, firmer by just over 30 ticks, before fading as above and moving marginally into the red. No move to the Flash PMIs, where the Manufacturing was strong while both Composite and Services were soft. From the series, the signs of slower growth are notable and one to watch ahead, as it may temper the hawkish impulses that were evident at the last BoE meeting, making the November meeting even more of one to watch.
- Germany sells EUR 1.65bln vs Exp. 2bln 3.40% 2047 and 2.90% 2056 Bund.
- Australia sells AUD 1.0bln 4.75% October 2037 bonds: b/c 4.16x, avg. yield 5.296%.
Commodities
- Focus for energy markets are three-fold. 1) US President Trump suggesting that he would back a ban on diesel exports. 2) A seemingly constructive bilateral meeting between Trump and Zelensky. 3) US envoys meeting with the Iranian delegation, which has been called “very productive”.
- On the first point. Trump has touted that he would back a ban on diesel exports, in a bid to ease domestic prices. Treasury Sec Bessent confirmed that officials were assessing the feasibility of either a partial or full ban of exports. This will impact downstream operations, and therefore, the reaction is made evident in the heating oil spread between Europe vs US; currently at USD 36.50/mt, yesterday’s close at USD -56/mt.
- As for geopolitics, the mood music has been positive on both the Russia-Ukraine, and US-Iran front. On the former, Ukrainian President Zelensky asked Trump to organise a Ukraine-US-Russia trilateral meeting; Trump suggested that Putin is willing to meet. Separately, CNN reported that Ukraine is ready to sign a defence deal with the US this week, but it may be postponed until the US is ready. On the US-Iran front, Trump noted that his top envoys had a constructive meeting with the Iranian delegation. He added that he thinks Iran will do something good. However, some sources familiar with the talks have dampened the recent optimism. Iran has not changed its position, whilst a US source believes that the chance of a deal is limited and major disputes and obstacles remain.
- Given the optimism surrounding geopolitics, crude benchmarks were initially lower this morning, but have since moved off worst levels to trade with incremental losses/flat. WTI is a touch lower and trades towards the upper end of a USD 88.71-90.52/bbl range, whilst Brent trades with incremental gains in a USD 94.08-96.11/bbl range.
- Spot gold is trading with losses of around a percent, and currently holds at the lower end of a USD 4,315.51-4,369.56/oz range. The yellow-metal is currently eyeing its 100-DMA (USD 4,313/oz), and further pressure could see gold hit its 50-DMA at USD 4,306.88/oz, ahead of the key USD 4,300/oz mark. Pressure today comes amidst a stronger USD and elevated front-end yields. Elsewhere, base metals are broadly in the red this morning, conforming to the downbeat risk tone. 3M LME Copper (-0.1%) currently holds towards the mid-point of a USD 14,666.28-14,862/t range.
- US Weekly Private Inventory Data (bbls): Crude +1.8mln (exp. -0.6mln), Gasoline -2.2mln (exp. +0.2mln), Distillate -2.2mln (exp. -0.5mln), Cushing +2.1mln.
- Iraqi Oil Minister said oil export volumes reached 70mln bbls in August and they are currently exporting more than 3mln bpd.
- Iranian Deputy Oil Minister for Planning said that around 50% of damaged capacity at South Pars has returned to service and production has resumed, according to Fars news.
- Ukraine Energy Minister met US Energy Secretary Wright to discuss energy security and the impact of the war, emphasising the importance of diplomatic efforts to achieve an energy truce.
- Spain is reportedly mulling capping gas prices to curb power bills, according to Cinco Dias.
Central Banks
- ECB’s Nagel said oil prices are not the only indicator, but have become more relevant over the past four years, while he is not so concerned by labour market developments and said monetary policy is being conducted between structural ambiguity and forward guidance. Furthermore, he does not see much uncertainty in markets about what drives the ECB’s policymaking decisions, as well as noted that rates are still in neutral territory and cannot exclude needing to go into mildly restrictive territory.
- ECB’s Makhlouf said second-round effects are not being seen yet.
- NBP’s Kotecki said we are approaching a serious discussion about an interest rate hike, possibly in November, adding that if interest rates are increased, it will be in small steps.
Geopolitics: Middle East
- US Envoy Witkoff said mediators will continue their work, and he hopes talks will be constructive and promising, while he confirmed he engaged in lengthy talks with the delegation from Iran.
- A US source attending the Iranian delegation meeting said the chance of a deal is limited and major disputes and obstacles remain between the US and Iranian delegations, according to Al Hadath.
- Diplomatic sources suggest that “Yesterday’s talks between the US and Iran did not achieve the minimum required to resume negotiations”, Hayom reported.
- Iranian Foreign Ministry spokesperson Baghaei said engagement with the US took place through a Qatari mediator to convey Iran’s conditions, Nour news reported.
- Iranian state media noted that Iran’s Foreign Minister Araghchi met with US envoy Witkoff at the UN General Assembly, with Tehran saying that the talk centered on its conditions for reopening the Strait of Hormuz.
- Iranian source said Qatar’s PM is acting as an intermediary between Iran and the US in New York and that the substance of Iran’s position is unchanged amid US dialogue, according to an Amwaj reporter.
- Diplomatic source in Tehran said a meeting between Iranian President Pezeshkian and US President Trump on the sidelines of the UN General Assembly is not on the agenda, journalist Kais reported citing Al-Akhbar.
- Iran’s Foreign Ministry stated that Foreign Minister Araghchi met with his Austrian counterpart and the two sides discussed and exchanged views on the most important international and regional developments, as well as bilateral issues of concern to both countries. Araghchi also met with his Iraqi counterpart and reviewed the progress of cooperation between the two countries in various fields, including economic, trade, consular, and security, and emphasised the continuation of efforts to develop relations in all areas of interest to the two countries.
- Explosions were heard near Iran’s Qeshm Island, which seemed to have originated from the sea, and there was no impact inside the territory of Qeshm Island, according to IRNA.
- French President Macron said France is ready to participate in an international operation of a defensive nature to protect navigation in the Strait of Hormuz, according to ABC News.
Geopolitics: Ukraine
- Russia’s Kremlin said ground for peace talks with Ukraine are still not in place and no concrete details of any plans of a high-level meeting on Ukraine.
- Ukrainian President Zelensky asked US President Trump for a winter arms package and expects an energy ceasefire push, according to WSJ.
- Ukraine is ready to sign a landmark drone defence deal with the United States on the sidelines of the UN General Assembly this week, although it may be at a later date when the US is ready to sign, according to CBS News citing sources.
- Ukrainian President Zelensky said that intelligence information indicates that Russia is preparing a massive attack on Ukraine.
- Russia said its forces hit Ukrainian defence and energy facilities and logistics centres, while Russian forces hit a cargo ship in the Black Sea
Geopolitics: Other
- US President Trump’s Board of Peace will unveil a six-month USD 2.45bln recovery plan for Gaza in its meeting with members on Wednesday, Axios reported citing sources.
- US Secretary of State Rubio said Greenland is critical to US national security and that the US cannot risk China or Russia establishing bases there.
- Taiwan is to maintain close contact with the US on arms sales.
US Event Calendar
- 7:00 am: Sep 18 MBA Mortgage Applications, prior -4.1%
- 9:45 am: Sep P S&P Global US Manufacturing PMI, est. 53.65, prior 53.9
- 9:45 am: Sep P S&P Global US Services PMI, est. 55.8, prior 56.5
- 9:45 am: Sep P S&P Global US Composite PMI, est. 55.25, prior 56
Central Banks
- 10:05 am: Fed’s Barr Speaks on Housing
- 12:00 pm: Fed’s Goolsbee Speaks in Podcast Interview
DB’s Jim Reid concludes the overnight wrap
Morning from Paris where getting around has proved even more difficult than normal due to various road closures ahead of a visit from the Pope on Friday. Markets were a bit like my travel map yesterday. All over the place. But they ultimately ended the session much where they’d begun, with the S&P 500 (+0.00%) flat on the day and 10yr Treasury yields (+1.1bps) edging higher. Brent crude retreated by -1.09% to close below $100/bbl for the first time in over two weeks after intra-day swings driven by a flurry of headlines around the UN General Assembly in New York. A more sanguine take just about dominated in the end amid news suggesting that the gap for achieving de-escalation between the US and Iran might be narrowing.
After reaching $102/bbl early on, Brent crude moved lower with the initial trigger being a Kyodo report that Iran would re-open the Strait of Hormuz within seven days if the US accepted demands including the lifting of its blockade on Iran. We also heard comments from the IRGC, with Iran’s state-run IRNA citing a spokesman who said that “If our national interests require us to negotiate alongside the war, we must negotiate”. And later on, Iran’s state media reported that in a meeting with Trump’s special envoy Witkoff, Iran’s Foreign Minister Araghchi said that Iran’s conditions to reopen the Strait of Hormuz include the lifting of the US naval blockade, release of frozen Iranian assets and the end of war across all ‘resistance’ fronts. So potentially suggesting that Iran might be willing to accept a narrower deal, having previously also demanded elements such as lifting of sanctions and reparations.
Of course, we’ve seen plenty of tentatively optimistic negotiation headlines come to little in recent weeks. Indeed, oil prices gave up some of their decline yesterday as Trump used his UN speech to justify the Iran war. Oil prices did then move lower again on the news of talks between US and Iran officials, which Trump called “very productive”. And aside from the negotiation headlines, we also heard that Saudi Arabia was in the early stages of restarting its East-West pipeline and was aiming for a meaningful if partial restart of flows by Saturday.
So after a round trip, Brent crude closed -1.09% at $99.02/bbl, some way above its low of $97.43/bbl in the European morning but is another -1.2% lower this morning. Meanwhile, European natural gas futures closed -1.96% lower at €71.90/MWh.
Despite the volatile newsflow, equities ended the day little changed, with the S&P 500 down a mere -0.001%. Tech stocks saw a better performance, with the NASDAQ (+0.45%) moving up to a fresh all-time high. That included further strong gains for chip stocks, with the Philly semiconductor index (+2.06%) posting a 6th consecutive gain. Trump himself also commented on AI in his speech at the UN, terming it “super intelligence” and rejecting attempts to control it. By contrast, financials (-1.98%) led the declines within the S&P 500, which appeared to be driven by concerns that AI could erode margins and fees.
In Europe, equities mostly saw modest gains, with the Stoxx 600 (+0.13%), CAC 40 (+0.20%), and DAX (+0.02%) rising. The exception was the UK’s FTSE 100, which fell -0.29%.
In the rates space, US Treasury yields initially followed oil prices lower, but then saw a rise by the close. So the 2yr yield (+0.8bps) inched up to a new two-year high of 4.76%, while the 10yr Treasury yield (+1.1bps) rose to 4.96%. Markets continued to price another 75bps of Fed hikes by next June, with Richmond Fed President Barkin noting the “risk that current elevated levels of inflation could affect future inflation”.
Looking forward to today, investors will be closely watching the US Treasury’s expected buyback announcement ahead of tomorrow’s 20-30yr operation. Last time there was a big market reaction as the operation size was beneath some estimates, leading to a sharp move higher in yields that day. So one to keep an eye on.
Bonds had a softer session in Europe, with yields moving higher across the continent. Yields on 10yr bunds (+0.7bps), OATs (+3.2bps) and BTPs (+1.8bps) all rose. Notably, the 10yr Franco-German spread was also back up to 104bps by the close, just shy of its 105bps peak last week which was the highest it’s been since the Euro crisis. In terms of ECB speakers, later in the evening we heard from Germany’s Nagel, who suggested the ECB may need to move from the current neutral stance “into the mild restrictive territory” if high energy prices persist.
There was also a variety of other geopolitical headlines from the UNGA, notably around Russia-Ukraine. Trump claimed that a Russia-Ukraine peace deal would be happening and Axios reported that US, European and Ukrainian officials were meeting last night to discuss proposals for de-escalation with Russia. It was also confirmed that US Secretary of State Rubio will be meeting with Russia’s foreign minister Lavrov today. While peace prospects appear dim, Ukraine’s President Zelenskiy told the WSJ that he thought Trump “will try to negotiate some energy ceasefire”.
Turning to Asia, markets are mixed this morning. As I check my screens, the KOSPI (+0.45%) is posting a moderate gain, with Japan’s markets still closed until tomorrow. Elsewhere, Chinese equities are under pressure, with the Hang Seng (-0.74%) underperforming both the CSI 300 (-0.50%) and the Shanghai Composite (-0.36%). Meanwhile, Australia’s S&P/ASX 200 (+0.08%) is little changed. US equity futures are also trading near flat, with those on the S&P 500 up +0.09%.
Early data showed Australia’s private sector activity lost momentum in September, with flash PMI figures from S&P Global showing the manufacturing PMI falling to 49.3 from 52.0, while the services PMI eased to 51.4 from 53.2. This pulled the composite PMI down to 50.8 from 52.7. The softer readings suggest a growing impact of elevated energy prices and higher borrowing costs on the economy, as markets widely expect the RBA to deliver another 25bps rate hike at its meeting next week.
To the day ahead, we’ll get September flash PMIs from around the world. Otherwise, central bank speakers include the Fed’s Barr, and the ECB’s Vujcic, Zigman, Kaasik, Cipollone and Lane.
Tyler Durden
Wed, 09/23/2026 – 08:50

