
AI CapEx And Earnings: What Happens When Growth Slows
Authored by Lance Roberts via RealInvestmentAdvice.com,
AI capex and earnings are now so tightly tied that spending doesn’t have to fall to hurt profits. It only has to stop accelerating.
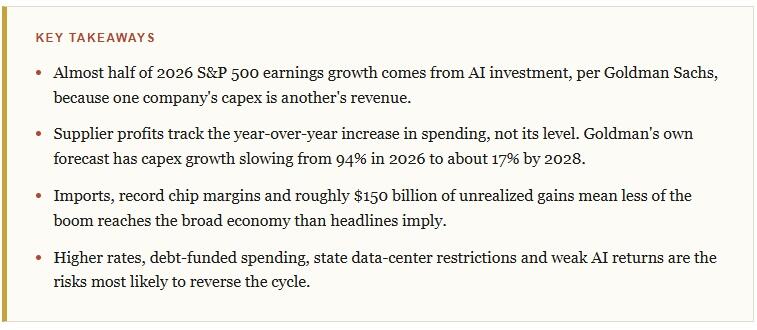
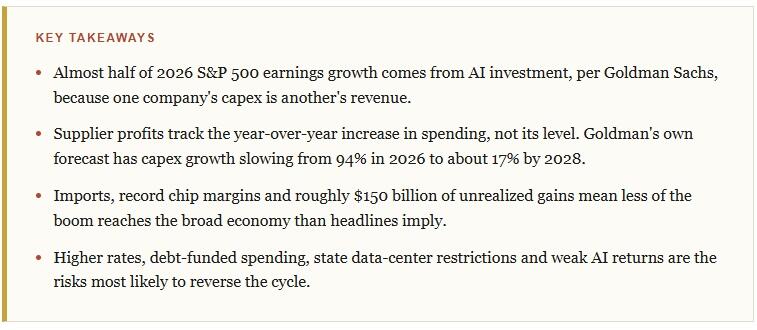
Almost half of the S&P 500’s earnings growth this year traces back to one activity: companies buying chips, servers, power gear, and concrete to build artificial intelligence. That’s the estimate Goldman Sachs published on September 23. It’s also the clearest statement yet of how tightly AI capex and earnings are now linked.1 Most investors read it as a story about the spenders. I think they’re looking at the wrong side of the ledger. Capex leaves one company’s bank account and appears on another company’s income statement, so the “AI earnings boom” depends less on how much is spent than on whether spending continues to grow.
Every Dollar Of Capex Is Someone Else’s Revenue
When a hyperscaler commits $10 billion to a data center, that money doesn’t vanish into a building. It goes to chip designers and memory makers, to the firms making transformers and cooling systems, and to contractors, electricians, and the local utility. Every one of them books it as “revenue.” Then their suppliers book revenue from them.
Jerome Levy worked this out early in the last century, and Michal Kalecki formalized it in the 1930s. For the economy as a whole, profits equal investment, minus household, government, and foreign saving, plus dividends.2 I’ve written about the Kalecki profit equation and the coming reversion before, mostly around deficit spending. Investment sits on the same side of that equation.
Here’s where it gets interesting. The seller books the revenue immediately. The buyer capitalizes the purchase and expenses it through depreciation over five or six years. In the year the money is spent, the economy records the supplier’s profit without recording the buyer’s expense. Such is why a capex boom is the most earnings-friendly event in the short run, and why I called it a “golden window” when I wrote about AI capex depreciation risk and record earnings in July.
The cycle runs in three stages. Rising spending lifts supplier revenue, margins and hiring. Flat spending freezes supplier revenue while the buyers’ depreciation keeps climbing, because every dollar that was “free” in year one starts showing up as an expense in years two through six, which is usually when the market has stopped paying attention. Falling spending turns it all into a drag. Only the first stage is fun.
How Big Is The AI Capex Boom Right Now?
Goldman puts hyperscaler capex at $800 billion in 2026, up 94% from 2025, heading to $1.2 trillion in 2027 and $1.4 trillion in 2028.1 FactSet’s July tally also lands near $800 billion for calendar 2026.3
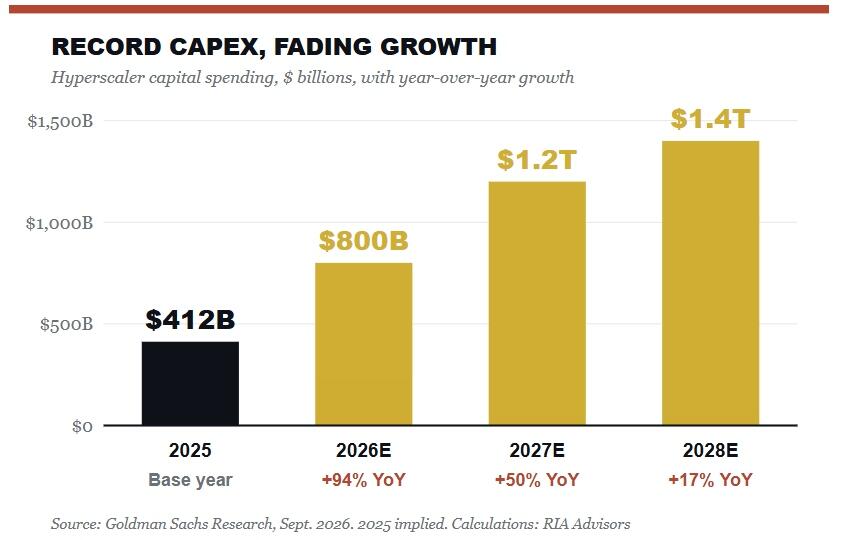
Hyperscaler capital spending rises from about $412 billion in 2025 to an estimated $800 billion in 2026, $1.2 trillion in 2027, and $1.4 trillion in 2028. Year-over-year growth falls from 94% to 50% to 17% over the same stretch. Source: Goldman Sachs Research, Sept. 23, 2026. 2025 implied from 94% growth. Calculations: RIA Advisors
Notice in the chart above that the bars keep getting taller. Spending continues to set records while the growth rate that drives supplier profits collapses.
That’s the relationship between AI capex and earnings in one picture.
So far, the payoff has been enormous. FactSet now expects calendar 2026 S&P 500 earnings growth of 32.8%, with Information Technology at 65%.
Why AI Capex And Earnings Hinge On The Growth Rate
Goldman offers a rule of thumb that does most of the work. A $250 billion surprise in 2027 capex, in either direction, would move S&P 500 earnings growth by roughly 6 percentage points.1 Goldman’s base case assumes capex rises 50% to $1.2 trillion and delivers about 11% earnings growth. I stretched that sensitivity to a few other outcomes.
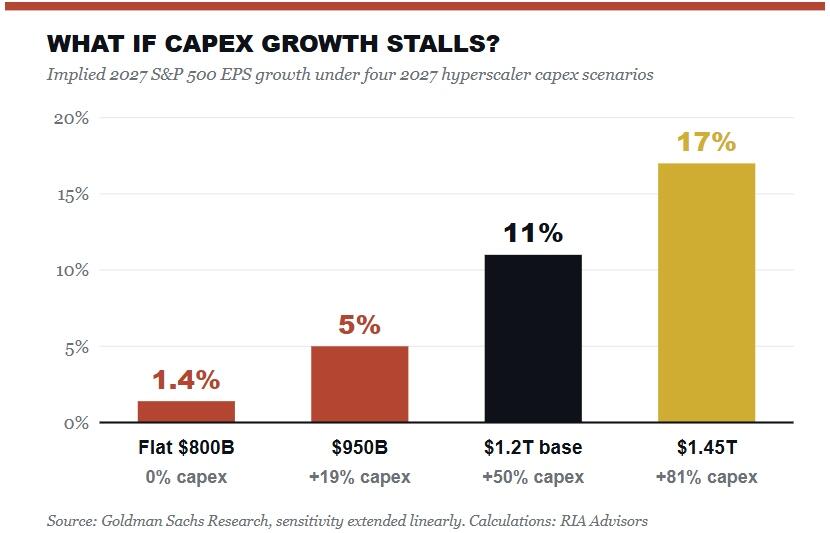
Applying Goldman’s sensitivity of about 6 points of EPS growth per $250 billion of capex, 2027 S&P 500 earnings growth would be roughly 1.4% if capex held flat at $800 billion, 5% at $950 billion, 11% at the $1.2 trillion base case, and 17% at $1.45 trillion. Source: Goldman Sachs Research. Sensitivity extended linearly. Calculations: RIA Advisors
If 2027 spending merely matched this year’s record, implied earnings growth would fall to about 1%. Read that again. The linear extension is my assumption, not Goldman’s, and real outcomes won’t be that tidy. The direction isn’t in doubt.
“Spending is still rising, so where’s the problem?” The problem is the size of each year’s increase. Goldman’s path adds roughly $390 billion in 2026 and $400 billion in 2027, then only $200 billion in 2028. The dollar increase drives supplier revenue growth, and that increase gets cut in HALF in 2028. Consensus already sees some of it, with FactSet’s 2027 earnings growth estimate at 16%.4
The reversal also hits harder than the spending cut itself, and this is the part I keep turning over. Suppliers expand for the demand they see. A transformer maker whose orders double adds a shift, hires welders and signs its own equipment orders, which becomes revenue for its suppliers in turn, and so on down a chain that runs all the way to the steel mill and the trucking company. That second round is why the boom feels broader than the hyperscaler numbers alone suggest. It works in reverse too. When growth stalls, the suppliers are left holding capacity, payroll, and inventory built for orders that stopped growing, and operating leverage runs the other way.
“The spending doesn’t have to fall to hurt earnings. It only has to stop accelerating.”
Where The AI Money Actually Lands
The flow-through is real, but the pipe is narrower than most assume. Much of the hardware is fabricated in Taiwan and Korea. A July Federal Reserve note found that import surges offset much of the gross investment in several quarters.5 An August analysis on Econbrowser concluded the direct GDP effect was roughly a wash outside the second quarter.6 Such leakage is part of why I argued that AI capex spending is masking economic weakness. The industrials and utilities Goldman names are real “winners,” but the fattest margins sit with a handful of chip designers.
Two pieces of the earnings number deserve a harder look. Semiconductor gross margins are running near 80%, roughly double their historical average. Goldman expects that boost to fade.1 Bob Farrell’s Rule #1 applies to margins as much as to prices: excesses revert to the mean. The second piece is stranger.
“Large technology companies recorded roughly $150 billion of unrealized investment gains in private companies in the second quarter of 2026, translating to 12% of S&P 500 EPS.” – Ben Snider, Chief U.S. Equity Strategist, Goldman Sachs Research
Those are marks, not cash. Such is the circular part of this cycle: hyperscalers invest in AI labs, the labs buy compute from the hyperscalers with that money, and the stakes get marked up at each new funding round. A mark can reverse just as quickly, and 12% of index earnings now depends on those rounds going well.
What Could Reverse The AI Capex Cycle?
The bigger risk is funding, not demand. FactSet expects free cash flow to hit roughly zero or turn negative in fiscal 2026 for every hyperscaler except Alphabet and Microsoft. The group already carries about $700 billion of debt and $820 billion of lease commitments.3 That money is being borrowed at rising rates. The Fed hiked on September 16 to a target range of 3.75% to 4.00%, its first increase since 2023. Chairman Kevin Warsh said “inflation is too high and has been for too long.”7 The 10-year Treasury yield closed at 5.10% on October 15th, after touching 5.24% on October 9th.8
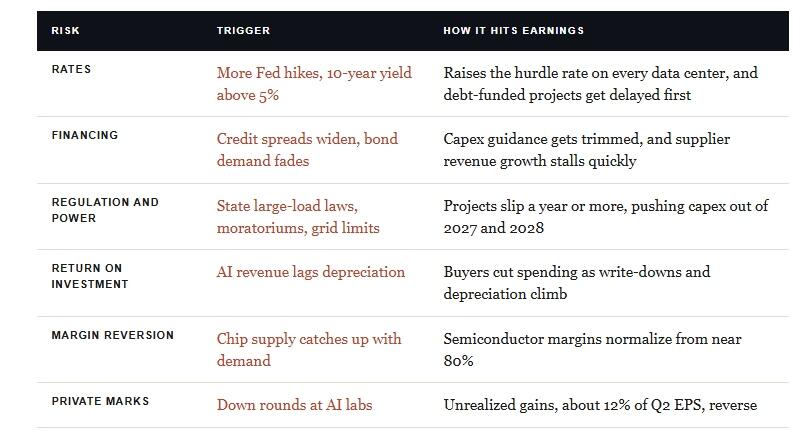
Regulation is the “slow-burn” risk. Moratorium bills were filed in at least nine state legislatures this year. Maine’s passed in April, then died on Governor Janet Mills’ veto.⁹ A federal AI Data Center Moratorium Act (S.4214) sits in a Senate committee with no action.¹⁰ No statewide moratorium has become law yet. However, any bill that does pass can push a project out a year or more, and a year of delay is exactly the kind of drop in capex growth that the earnings math above can’t absorb.
History has a template. From early 1996 to late 2000, U.S. communications equipment investment more than doubled, from about $62 billion a year to over $135 billion.11 Within one year, it fell by nearly a third.
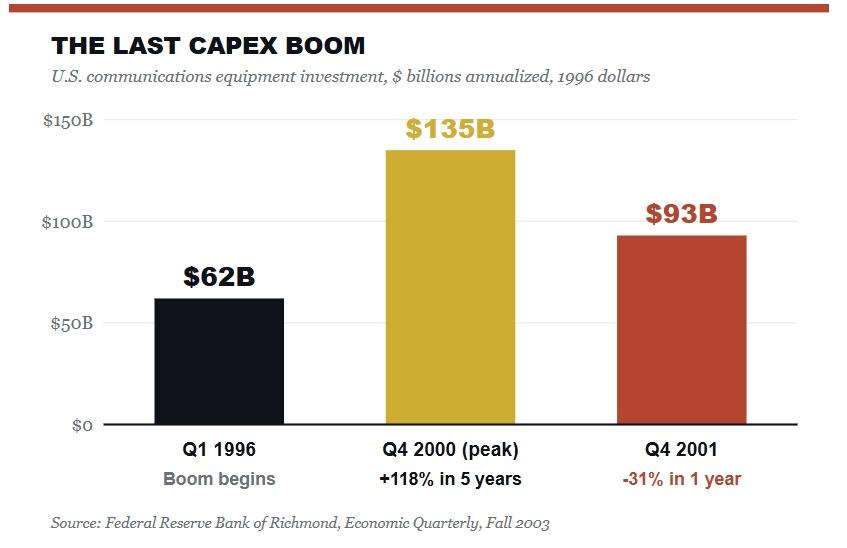
U.S. communications equipment investment rose from about $62 billion in early 1996 to more than $135 billion at the fourth-quarter 2000 peak, then fell to under $93 billion a year later, a drop of roughly 31%. Source: Federal Reserve Bank of Richmond, Economic Quarterly, Fall 2003
The fiber was real. Internet traffic eventually showed up. Shareholders of the companies that built it still got wiped out. Such is how capex cycles usually end, with the asset intact and the “investment thesis” in pieces.
Where The Bulls Are Right
The bulls have a strong case. The S&P 500 trades at 19x forward earnings, right on its 10-year average of 19.1x, because earnings have outrun prices.4 Those spenders are among the most profitable companies in the world, and Goldman sees 11% earnings growth in both 2027 and 2028.1
I like the AI trade. Mostly. What keeps nagging me is that the “reasonable” 19 multiple sits on an “E” that includes the capex flow-through, record chip margins, and a mark-to-market gain on private stakes, none of which is likely to repeat at this pace. A normal P/E on an abnormal E isn’t cheap; it only looks that way. Goldman itself notes that the cyclically adjusted P/E sits near record highs.1
What AI Capex Means For Your Portfolio
I’m fairly confident 2027 holds up, since the dollar increase in spending is still about $400 billion. Past that, my confidence drops sharply. The practical move is to watch the rate of change in AI capex and earnings, which few investors track. Each earnings season, compare the increase in capex guidance with the prior year’s increase, not the prior year’s level. Watch hyperscaler free cash flow and credit spreads, because financing tends to crack before demand does. Watch chip margins for the first sign of reversion.
Then check your own exposure. A “passive” S&P 500 index fund owns this cycle whether you meant to or not, because the spenders and the suppliers crowd the top of the index, which means the same few companies sit on both sides of the trade. Rebalancing to your targets after a run like this is risk management, not a market call. The trade-off: trim too early, and you give up return if Goldman is right. I’d rather pay that cost than the one the AI capex bill could bring later. The open question remains whether AI capex spending leads to positive outcomes that beat its cost of capital.
The link between AI capex and earnings carried roughly half of this year’s profit growth, and that support fades once spending stops accelerating, even at a record level.
The earnings bill doesn’t arrive when the spending stops. It arrives when the spending stops growing.
If your portfolio has quietly become a bet on the AI capex cycle, it’s worth knowing how much of your return depends on spending that has to keep accelerating. That’s the conversation we have with investors every day at RIA Advisors. Schedule a complimentary portfolio review, and let’s pressure-test your exposure together.
Questions This Article Answers
How does AI capex affect S&P 500 earnings? One company’s capex is its suppliers’ revenue, while the buyer spreads the cost over years through depreciation. Goldman Sachs estimates that almost half of the 2026 S&P 500 earnings growth comes from AI investment.
Can AI capex hurt earnings without falling? Yes. Supplier profits track the yearly increase in spending. Applying Goldman’s sensitivity, flat 2027 capex at $800 billion implies roughly 1% S&P 500 earnings growth.
How much are hyperscalers spending on AI? Goldman Sachs estimates hyperscaler capex of about $800 billion in 2026, up 94%, rising to $1.2 trillion in 2027 and $1.4 trillion in 2028. FactSet’s estimate for 2026 is similar.
What could end the AI capex boom? Higher interest rates, tighter financing as free cash flow shrinks, state limits on data centers, weak AI returns, and falling chip margins.
Tyler Durden
Mon, 10/19/2026 – 15:10

