
Boeing Shares Crater Most In 18 Months After Delivery Outlook Cut
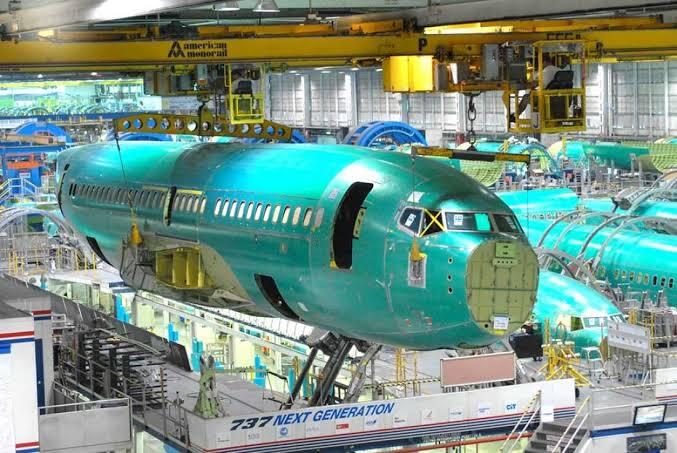
Boeing shares cratered in the US cash session by late morning in New York after it slashed its commercial aircraft delivery outlook because it needs more time to ramp up to sustainable production rates.
The struggling planemaker expects to miss its full-year production target of 500 737 aircraft – its cash cow aircraft – and deliver about 90 787 Dreamliners, the bottom tier of its guidance range.
“I’ve said before, our progress is not always going to be perfectly linear, but we continue to improve, and I’m confident we are on the right track,” CEO Kelly Ortberg told investors on a third-quarter earnings call.
The warning to the outlook overshadowed stronger-than-expected cash generation and revenue. Boeing reported a core loss of 34 cents a share, wider than the Bloomberg Consensus estimate of a 21-cent loss, while revenue rose 4% to $24.2 billion.
Snapshot of Third Quarter Earnings:
- Adjusted free cash flow $464 million, estimate $325.1 million (Bloomberg Consensus)
- Commercial Airplanes revenue $10.72 billion, -3.4% y/y, estimate $10.94 billion
- Defense, Space & Security revenue $7.94 billion, +15% y/y, estimate $7.41 billion
- Global Services revenue $5.57 billion, +3.8% y/y, estimate $5.47 billion
- Operating cash flow $1.50 billion, +33% y/y, estimate $1.24 billion
- Backlog $745 billion
- Commercial airplanes operating loss $697 million vs. loss $5.35 billion y/y, estimate loss $360.8 million
- Defense, Space & Security operating earnings $492 million vs. $114 million y/y, estimate $243.5 million
- Global services oper earnings $1.02 billion, +8.6% y/y, estimate $983.9 million
- Revenue $24.19 billion, estimate $23.85 billion
- Loss per share 26c
- Core loss per share 34c vs. loss/shr $7.47 y/y, estimate loss/shr 21c
Wall Street analysts highlighted persistent losses in Boeing’s commercial aircraft business and uncertainty over its cash-flow recovery, despite better cash generation in the quarter.
- JPMorgan’s Seth Seifman: Commercial aircraft sales met expectations, but margins missed by about 280 basis points because of rising costs. Losses on a unit-accounting basis have remained around $1.3 billion for five consecutive quarters, underscoring limited progress on profitability. Overweight; $290 target.
- Jefferies’ Sheila Kahyaoglu: Flagged Boeing’s failure to reaffirm its 2026 free-cash-flow guidance. Production-rate timing weighed on commercial margins, although the 737 program continues moving toward stabilization at 47 aircraft a month. Buy; $265 target.
- RBC’s Kenneth Herbert: Highlighted weaker-than-expected core earnings and a larger commercial aircraft loss than forecast. The focus remains on the drivers of free-cash-flow growth in 2027 and 2028. Outperform; $235 target.
- Bloomberg Intelligence’s George Ferguson: Offered a more reassuring liquidity assessment, saying $1.5 billion in quarterly operating cash flow provides a cushion against slow delivery improvements and helps preserve roughly $20 billion in liquidity.
“Looking ahead, expectations are rising, and they should,” Ortberg told employees in a memo, adding, “We have a stronger foundation than a year ago, but we also have more work to do to deliver on our backlog, strengthen our culture, and improve how we work every day.”
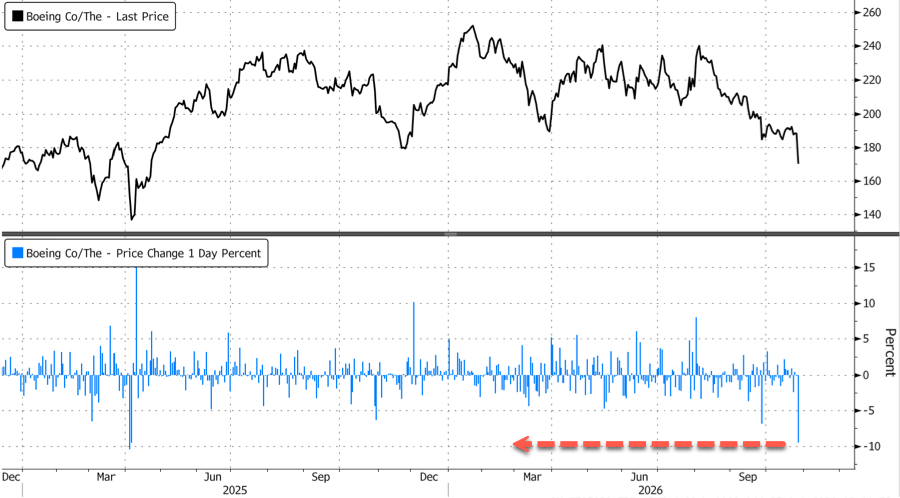
The cut to its full-year aircraft delivery outlook and a wider-than-expected loss in its commercial unit sent the stock down about 10% in late-morning trading, its largest intraday decline in 18 months, or since April 3, 2025.
“Boeing’s third-quarter results come a day before rival Airbus SE is set to report its own financial performance. Airbus has pulled ahead of Boeing on aircraft deliveries, but the Franco-German planemaker hasn’t been immune to its own quality and supply hiccups this year,” Bloomberg noted.

