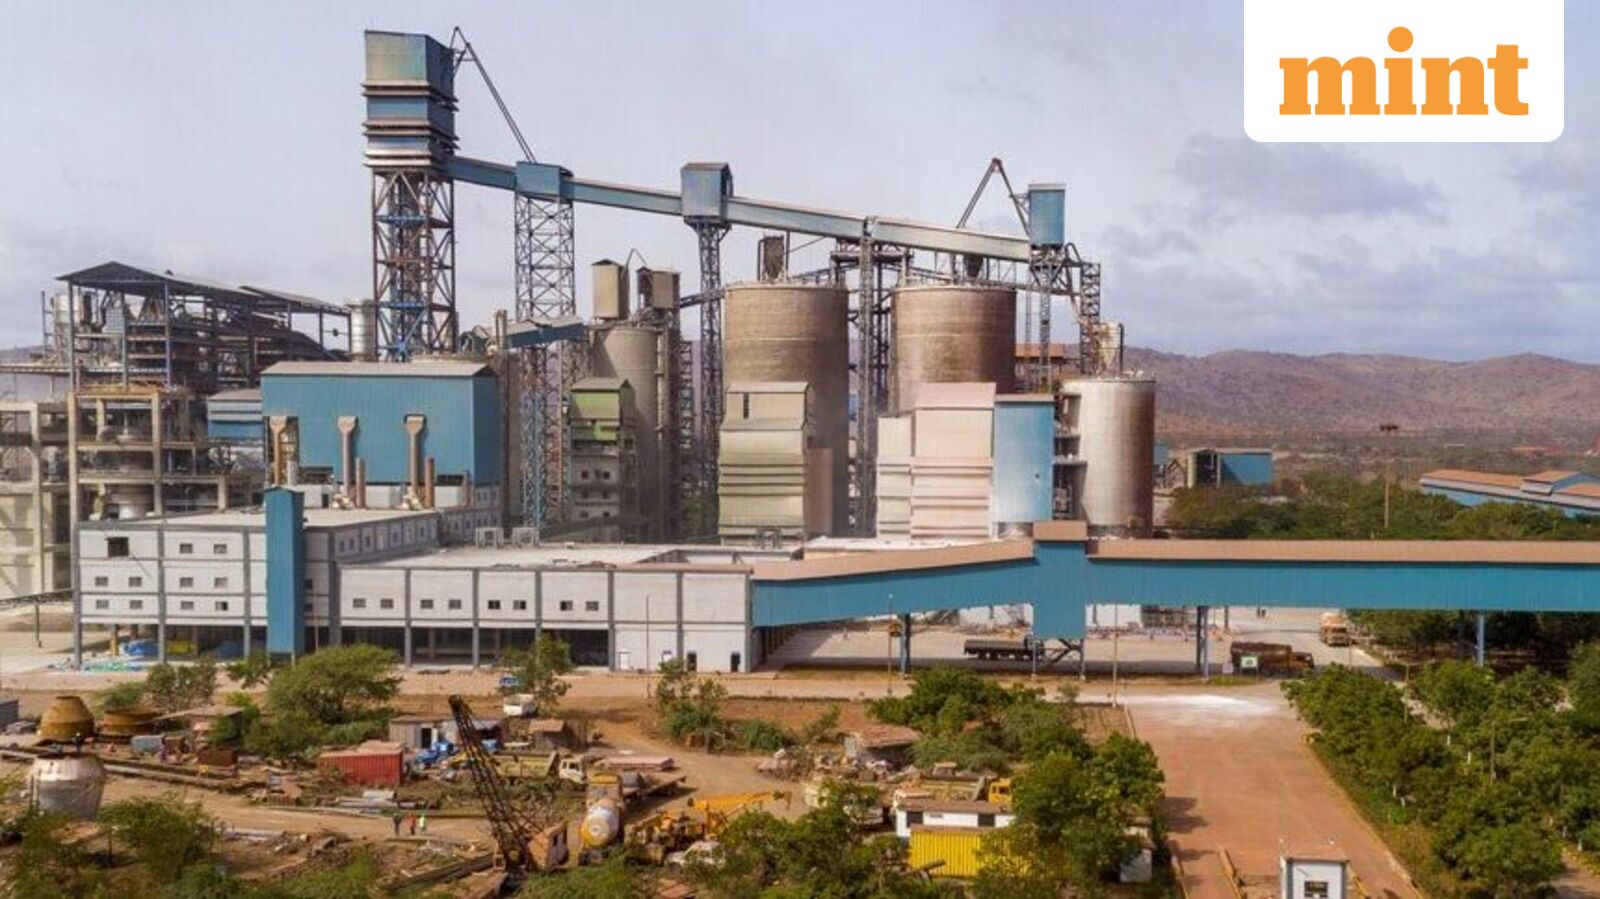
Home JSW Cement’s regional diversification is comforting, but costs are more important now By admin September 21, 2026 0 13 FacebookTwitterPinterestWhatsApp JSW expects volume growth in the high teens in FY27, but costs are a near-term re-rating trigger.JSW expects volume growth in the high teens in FY27, but costs are a near-term re-rating trigger. Share FacebookTwitterPinterestWhatsApp Previous articleOracle Financial Services share price falls 6.5% today | What’s behind the plunge?Next articleTop stocks to buy for short term: Jigar Patel recommends Castrol, HDFC Life, Gabriel – Check target price, stop loss adminhttp://arzu159951-010-site2.ntempurl.com Related Articles CEO who posted ‘Lake America’ sweatshirt photos is no longer with the company NSE's IPO launches at $46.9bn valuation Flock And Other Tech Firms Decline Senate Testimony On Mass Surveillance Latest Articles CEO who posted ‘Lake America’ sweatshirt photos is no longer with the company NSE's IPO launches at $46.9bn valuation Flock And Other Tech Firms Decline Senate Testimony On Mass Surveillance Rogue AI “Regulation” – A Potential Worst Case Scenario U.S. markets end mostly lower on Thursday Load more