
Quality Over Quantity: The Missing Signal In Jobs Data That Explains The Vibecession
Authored by Lance Roberts via RealInvestmentAdvice.com,
Recession Indicators Turned Green. Job Quality Hasn’t.
October’s jobs report pushed the headline recession indicators back to green, but “labor hoarding” explains why the earnings boom still isn’t reaching full-time workers.
Key Takeaways
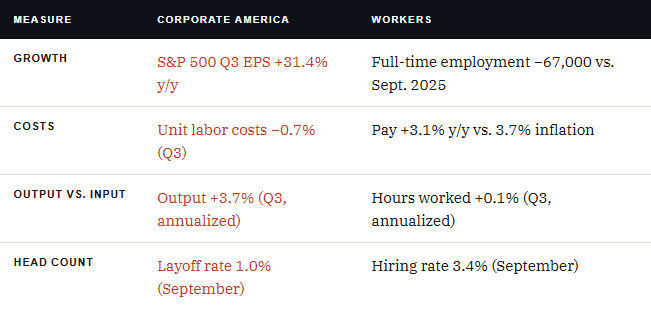
- S&P 500 earnings are on track to grow 31.4% in the third quarter, yet fewer Americans work full-time today than in September 2025.
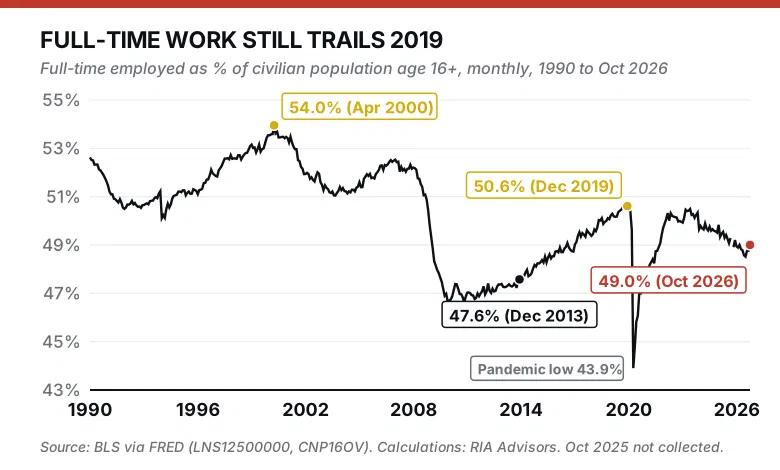
- October payrolls beat every forecast at 165,000, but full-time employment, at 49.0% of the working-age population, remains well below its 2019 level of 50.6%.
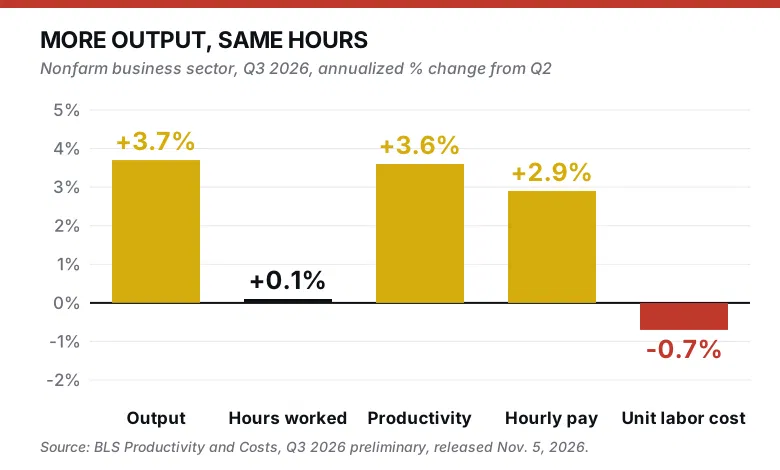
- Companies are “hoarding” labor: output rose 3.7% last quarter while hours worked rose 0.1%, so productivity, not hiring, is carrying profits.
- Involuntary part-time work jumped 339,000 to 4.8 million in October, and pay growth of 3.1% still trails 3.7% inflation.
- The recession indicators flashing green – claims and layoffs – are the ones labor hoarding suppresses the longest.
Here is the puzzle investors face right now. S&P 500 companies are on track to report 31.4% earnings growth for the third quarter, the eighth straight quarter of double-digit gains. Last Friday, the October jobs report beat every forecast, with payrolls up 165,000 and unemployment back down to 4.1%. On the surface, the recession indicators have turned green. Beneath the surface, the quality of the jobs tells a different story. Such is the question worth answering: is the labor market healing, or are companies still “hoarding” labor while profits do the heavy lifting?
Why The Recession Indicators Disagree
Let’s start with the economic indicators that say all is well. In the most recent reports:
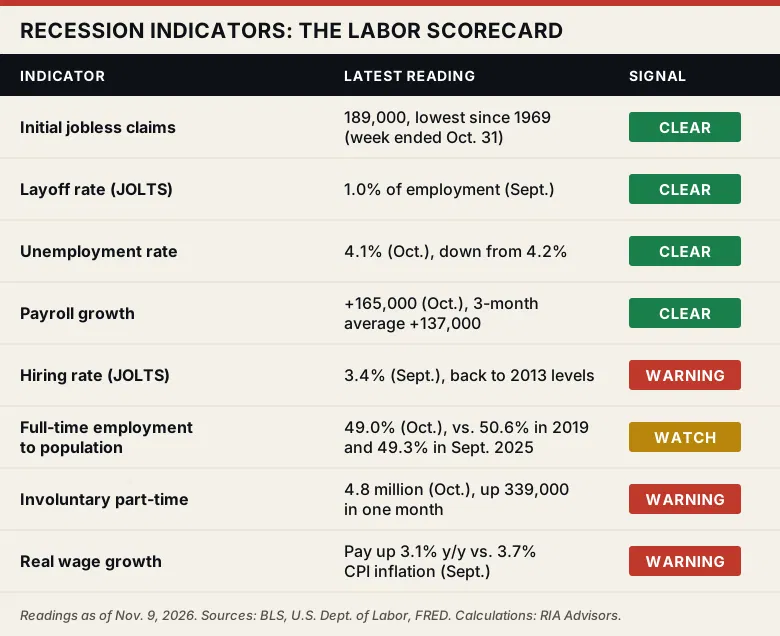
- Initial jobless claims fell to 189,000 in the week ended October 31, the lowest reading since 1969.
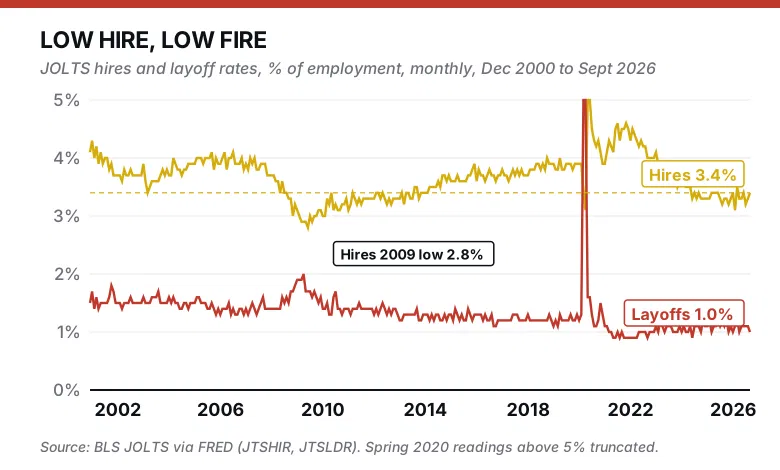
- The Job Openings and Labor Turnover Survey (JOLTS), which printed a layoff rate of 1.0% in September, near the floor of its 25-year history
- The October payrolls rose 165,000 against a consensus near 65,000, and revisions added 84,000 jobs to August and September.
In other words, if your only recession indicators are layoffs, claims, and the headline payroll count, there is no recession anywhere in sight.
Now look at the other half of the labor data. The JOLTS hiring rate sits at 3.4%, in line with its 2013 average and well below the 3.9% pace of 2019. The number of people working part-time because they can’t find full-time work jumped by 339,000 in October to 4.8 million. Workers unemployed for six months or longer now make up 27.6% of the unemployed. Average hourly earnings grew 3.1% from a year earlier, still short of the 3.7% inflation rate.
Employers are not firing anyone, and they are hiring far more cautiously than the headline suggests. That is the “low hire, low fire” economy, and the chart below shows how unusual the combination is. In 2009, hiring collapsed as layoffs surged and companies shed workers as quickly as they could process paperwork. Today, hiring has slowed to 2013 levels with layoffs near record lows. The two lines usually move together. This time they are not.
Labor Hoarding: I’ve Seen This Movie Before
In early 2014, I wrote a piece arguing that the headline jobs data was missing the point. My view was that the only employment chart that mattered was full-time employment relative to the working-age population. The reason was simple. Full-time jobs pay the wages that support household formation, consumption and tax receipts. Part-time work and headline payroll counts don’t.
The argument centered on a behavior I called “labor hoarding.” Businesses had cut costs to the bone after the financial crisis and could cut no further. To wit:
“At this point businesses have to begin to ‘hoard’ what labor they have, maximize that labor force’s productivity (increase output with minimal increases in labor costs) and hire additional labor, primarily temporary, only when demand forces expansion.”Lance Roberts, ” – The Only Employment Chart That Matters, 2014
Swap the 2014 headwinds for today’s tariffs and energy costs, and that description fits almost word for word. So let’s update the chart. Full-time employment as a share of the civilian population age 16 and over peaked at 54.0% in April 2000. It stood at 47.6% when I wrote that piece and recovered to 50.6% by the end of 2019. As of October, it’s 49.0%, roughly where it was in 2016 and still below September 2025’s 49.3%.
Let’s dig into the BLS’s household survey for October. That report showed a jump of 714,000 full-time workers, a welcome sign. However, the household survey swings widely from month to month, and one month doesn’t make a trend.
What was important in that data was that there are still 67,000 fewer people working full-time than in September 2025. However, the working-age population has grown by nearly 1.5 million over the same period. Since November 2023, full-time employment has increased by just 271,000, even though there are 7.9 million more working-age Americans. Companies are protecting the workers they have and adding very few new full-time positions. Calling that a “healing” labor market is generous.
4.4 Million
Additional full-time workers the U.S. would have today if the full-time employment ratio were back at its 2019 level.
Where The Earnings Boom Actually Comes From
If companies aren’t adding full-time workers, how are earnings growing 31%? Part of the answer arrived last week. Nonfarm productivity rose at a 3.6% annualized rate in the third quarter as output grew 3.7% and hours worked rose just 0.1%. Unit labor costs fell 0.7%. In other words, companies produced more without paying for more hours, and the difference dropped straight to the bottom line.
Pay attention to this data. It is the textbook payoff from “labor hoarding.” The playbook is simple:
- Hold headcount steady,
- Squeeze more output from the existing workforce, and
- Let margins expand.
This is completely rational behavior for any single company. However, when it spans the entire economy, it means the profit boom is not reaching paychecks.
The other piece is concentration. Energy and Information Technology have delivered the biggest upside earnings surprises this season, and as of mid-October, Micron and NVIDIA were the two largest contributors to S&P 500 earnings growth. Elevated oil prices fattened energy profits, while AI spending fattened chip profits.
Neither industry employs many people relative to what it earns. As I discussed in “Capex Spending On AI Is Masking Economic Weakness,” a narrow capex boom can mask economic weakness while the broader economy stalls. Some of those profits are also flattered by accounting timing, a point I made in “AI Capex Depreciation Risk Is The Catch To Record Earnings.”
Is A Recession Coming? The Case Against My View
The other side of this debate has merit, and October’s jobs report handed it more ammunition. Payrolls beat every forecast, and unemployment fell back to 4.1%. Job openings rose by 333,000 in September, lifting the openings rate to 4.5%. Quits hit an 18-month high the same month, which usually means workers feel confident enough to leave. Claims at a 57-year low are hard to argue with. Here’s how one strategist read Friday’s numbers:
“[The report] is a strong rebuttal to fears that the economy is heading into a meaningful slowdown.” – Seema Shah, Chief Global Strategist, Principal Asset Management
Productivity growth is also good news in its own right. If the AI buildout is lifting output per hour, the economy can grow faster without adding workers or adding inflation.
“You made this same argument in 2014, and the economy kept growing for six more years.” Yes, that is true. However, the process of “labor hoarding” doesn’t cause a recession on its own. It changes HOW the next one unfolds. In 2014, the Fed held rates at zero and ran QE, which bought companies years to grow their workforces. On October 28, the Fed held rates at 3.75%-4.00%, and two members dissented in favor of a rate hike. After Friday’s report, investors now lean toward a December hike. There is no zero-rate cushion this time to buy companies that kind of patience.
What These Recession Indicators Mean For Investors
For investors, let’s go back to the beginning. Pay attention to which recession indicators are flashing green. They’re the layoff numbers and the headline counts. Crucially, the payroll survey doesn’t distinguish between full-time and part-time jobs. That distinction matters in a month when involuntary part-time work jumped by 339,000. Furthermore, both claims and layoffs are precisely the signals labor hoarding suppresses, because a company that hoards workers doesn’t let anyone go until it has to. Then it lets a lot of people go at once. When hoarding ends, claims don’t drift higher. They jump.
So, what will eventually force corporate hands is falling profit margins. For now, productivity gains and falling unit labor costs are protecting profits. But wage growth of 3.1% still trails inflation at 3.7%. As I laid out in “Real Wages 2026: Why Consumer Stocks Feel It First,” households are covering the gap with longer hours, less saving, and more credit.
Therein lies the risk. When demand softens enough that output stops growing, and there’s no more productivity to squeeze, then headcount becomes the only lever left. As is always the case, a “low fire” economy turns into a “high fire” one almost overnight.
“Labor hoarding doesn’t prevent a recession. It delays the layoffs, and then it delivers them all at once.”
For investors, the practical point is that the earnings estimates underpinning today’s valuations assume this setup will persist. Analysts expect 28.4% growth in the fourth quarter and 33.3% for all of 2026. Those numbers depend on a narrow group of sectors and on margins built by not hiring. That makes this a good time to review how concentrated a portfolio is in the handful of companies producing those earnings. It’s also worth knowing in advance which signal would change your mind. For me, it’s a sustained break higher in weekly claims, particularly continuing claims, which recently ticked up to 1.718 million. Claims are the recession indicator that hoards the longest, which makes them the ones that matter most when they finally move.
Bottom Line
The labor data tells you how long the earnings boom can last, and the answer is only as long as companies can keep avoiding the need to hire.
October’s jobs report bought the bulls another month. Watch the claims data anyway. The quietest layoff market in 57 years is also the one with the least room for error.
