
Goldman Warns Nightmare Refining Crisis Could Prolong Diesel, Gas Price Pain Through 2027
Goldman energy analyst Nikhil Bhandari warned in a note on Monday that the global refining system is too stretched to support a full recovery in fuel demand while inventories rebuild. This suggests that fuel prices will remain elevated into next year.
Bhandari told clients that refining margins must remain elevated to restrain consumption and limit restocking, keeping demand within the industry’s ability to supply diesel, gasoline and jet fuel.
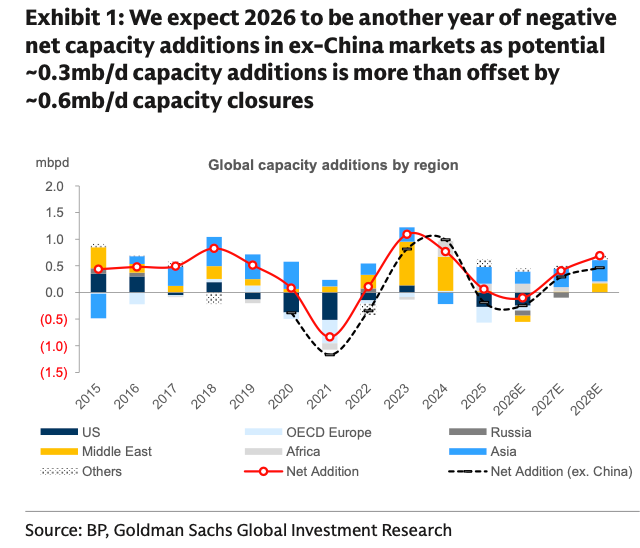
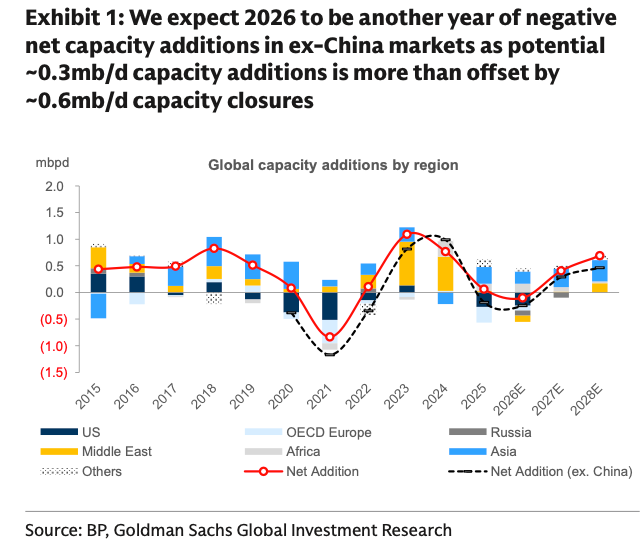
On an ex-China basis, Bhandari expects 300,000 barrels a day of refining capacity additions in 2026 to be offset by 600,000 barrels a day of closures, leaving another year of net capacity losses.
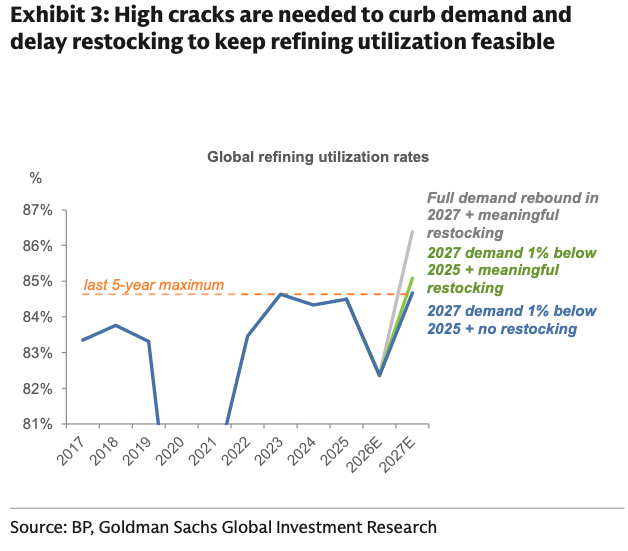
Bhandari said if demand rebounds to 1% above 2025 levels while buyers attempt to replace half of this year’s inventory draws, refinery utilization would have to reach unprecedented levels. This is a territory that he said, “We do not view as operationally realistic.”
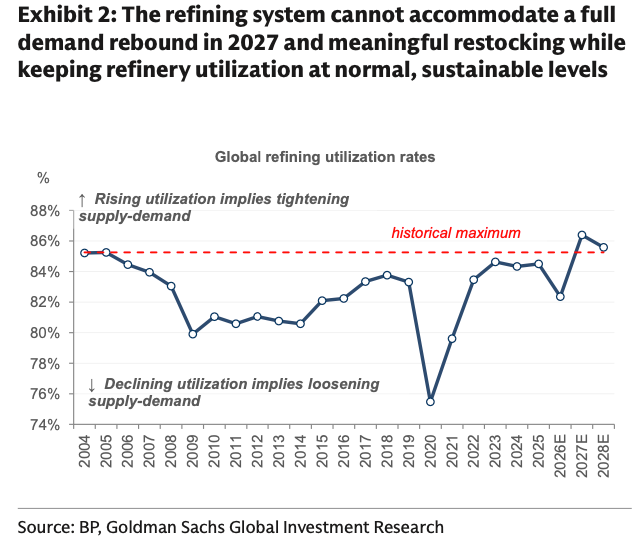
To keep utilization near the highest level seen this decade, the analyst says one possible combination would require demand to remain 1% below 2025 levels and no inventory rebuilding in 2027.
In other words, an uncomfortable reality is setting in: fuel prices need to stay high enough to keep consumption subdued.
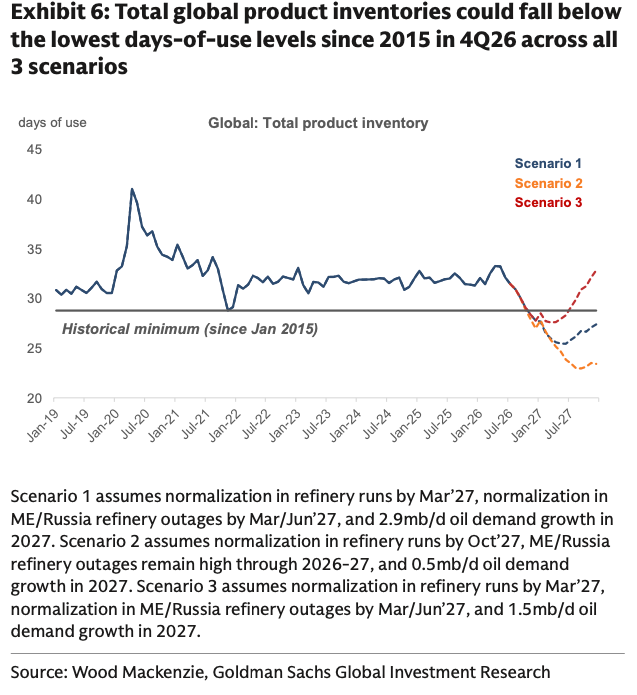
He provided clients with three scenarios spanning different recovery paths for refinery operations and global oil demand but warned global refined-product inventories could fall even more by the end of the year, possibly to 2015 levels measured in days of consumption during the fourth quarter of 2026.
Bhandari expanded on his refining supply-demand framework:
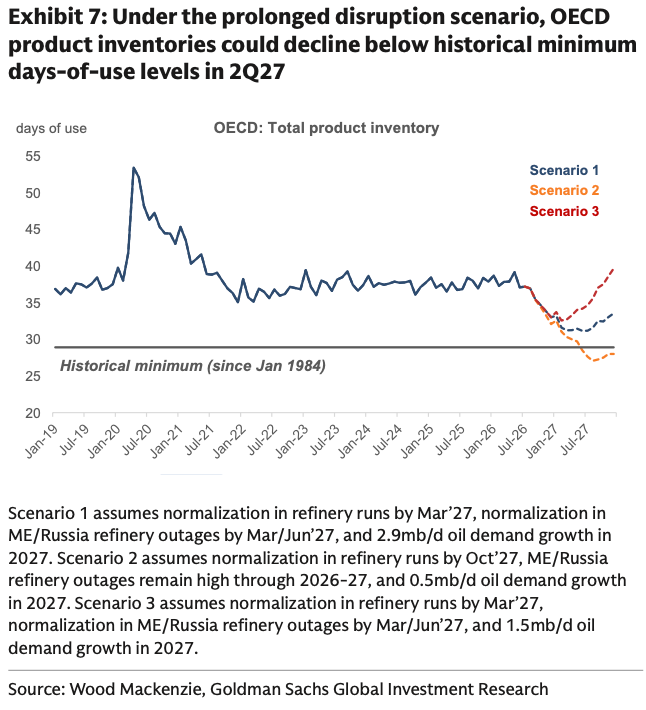
Scenario 1 assumes global refinery runs back to normal levels by March 2027, followed by the resolution of Middle East refinery outages by June 2027 and Russian disruptions by December 2027, paired with a robust 2.9 mb/d recovery in global oil demand in 2027.
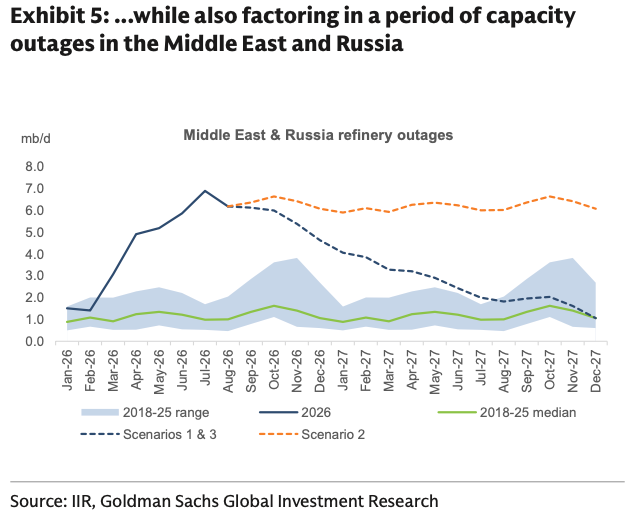
Scenario 2 models a prolonged disruption, delaying the normalization of global refinery runs to October 2027. Under this scenario, Middle East and Russian refinery outages remain elevated at 5.0 mb/d above seasonal norms through the remainder of 2026 and 2027, paired with a sluggish global demand growth of 0.5 mb/d.
Scenario 3 mirrors the refinery runs and outage normalization timeline as Scenario 1, but assumes a more modest global oil demand growth of 1.5mb/d.
Across all 3 scenarios, we assume refinery utilization of the operating fleet returns to the highest 3-month average seen over the past 5 years post refinery runs normalization (Exhibit 4-Exhibit 5).
We note total global product inventories could fall below the lowest days-of-use levels since 2015 in 4Q26 across all 3 scenarios (Exhibit 6), and OECD product inventories (inclusive of strategic reserves) in 2Q27 could fall below their historical minimum days-of-use level last seen around 2003 (Exhibit 7).
For refiners with access to steady crude flows, tight global refining capacity could create perfect conditions of strong margins and substantial cash generation. Bhandari highlights Valero and Marathon Petroleum in the US, S-Oil and Thai Oil in Asia, and Repsol, Neste and Helleniq Energy in Europe as potential beneficiaries.
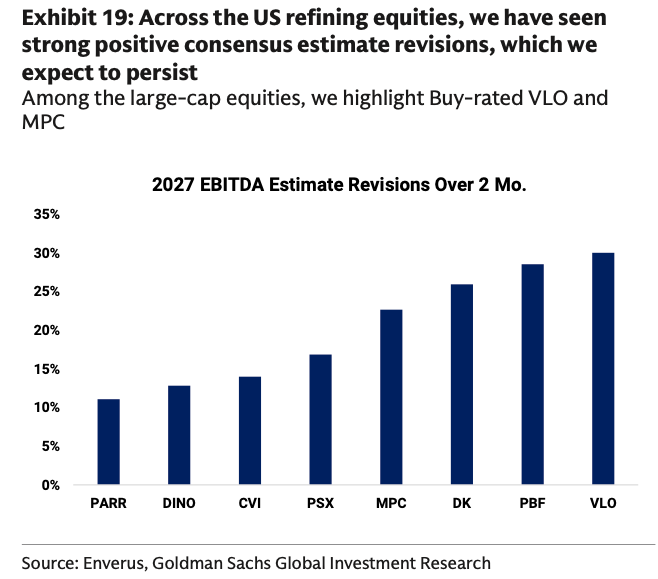
Diesel and jet fuel remain at the epicenter of the global supply squeeze. Bhandari’s warning of a global refining system “stretched for longer” suggests those favorable refining economics could come alongside elevated fuel costs that would pinch consumers’ pocketbooks.
Last week, Goldman commodity experts Yulia Zhestkova Grigsby and Daan Struyven warned that the diesel crisis is setting up the next squeeze: gasoline.
Professional subscribers can read the full note here at our new Marketdesk.ai portal.
Tyler Durden
Tue, 09/22/2026 – 14:10

